 Capital Wealth Daily
The Peace Trade Issue
Our read of the July 10 Wall Street Journal (Thursday, July 9 close). Every story with its tickers, and what the model books did about it.
The AI trade changed lanes, out of the giants and into the suppliers. We followed the money.
The peace trade won, and the money that came back didn’t go back to the same names. Micron (MU) jumped 4.5% to $991.64 on a $250 billion U.S. manufacturing plan “driven by surging demand for memory in the AI era.” Sandisk (SNDK) rose +7.6%, Marvell (MRVL) +5% and ON Semi (ON) +4.4%. Western Digital (WDC) and AMD were among the S&P’s biggest gainers. Nvidia (NVDA, −0.7%), Microsoft (MSFT, −2.5%) and Alphabet (GOOGL) sat it out. Semis rose +3.1% Thursday and are up +83% YTD. The S&P closed within 1% of its record. KeyBanc cut Salesforce (CRM) because customers’ data “is not in order” for AI. That dragged ServiceNow (NOW) and Workday (WDAY) down with it, while our Palantir (PLTR) held green.
Our ReadYesterday we said MU stays benched until the contract shows up. It showed up, $250 billion of it. Micron moves off the watch bench and into the memory sleeve of the tactical books, joining AVGO and TSM. NVDA, MSFT and GOOGL stay held, not chased. One week of leadership change is information, not a verdict. CRM stays off the add list. Rotation inside a theme is why we own the sleeve, not one horse. Your income plan should never depend on guessing which chip wins.
The Stories
7 stories · 3 pictured · 4 listed
“Once the shelf is bare, there’s nowhere to turn.” We keep the insurance.
Chevron (CVX), Exxon (XOM) and ConocoPhillips (COP) stay reinforced on the down day. Thin buffers are exactly what the insurance sleeve insures against, and it pays a dividend while it waits. The pipes (KMI, WMB) keep tolling. The refiners (MPC, VLO) stay benched at 52-week highs. Dangote’s listing goes on the watch list for the income book’s world tour.
An $80 billion debt pile walks into Hollywood. We’ll wait in the lobby.
PARA and WBD stay avoided. We don’t own turnarounds financed at 6.5 times leverage, no matter how famous the logo on the water tower. When a deal’s bonds pay 8.43% while the equity deck promises synergies, the bond market has graded the slideware. It gave it a C-minus. NFLX stays on watch until engagement stabilizes. If the merger creates value, it’ll show up in free cash flow. We can buy it then, cheaper than the excitement.
Boeing’s MAX 7 gets a date, and Boeing gets its signature back.
BA moves up the conviction ladder. It is reinforced in the tactical books on a dated, verifiable catalyst that turns a parked backlog into cash. We size it like the turnaround it still is. The defense sleeve around it (LMT, RTX, AVAV) holds. Peace trades come and go, and defense budgets have noticed neither. Homebuilders stay off the list. The 30-year sits at 6.49%, and June existing-home sales fell to a 4.09 million pace at a record $440,600 median.
- Heard on the Street · IncomeThe tobacco trade came in from the cold. The income book is checking its coat.
- Consumer · The $3.85 TaxPepsi beat and fell. Costco grew 10.6% and fell. The gas pump is undefeated.
- Credit · Investor BewareSpaceX’s bonds had a rough week. The bond market doesn’t do autographs.
- Retirement · Your Health DollarsThe Medicare Advantage fight is back. Here is what retirees should actually compare.
Off Duty & The Life File
5 stories · 3 pictured · 2 listed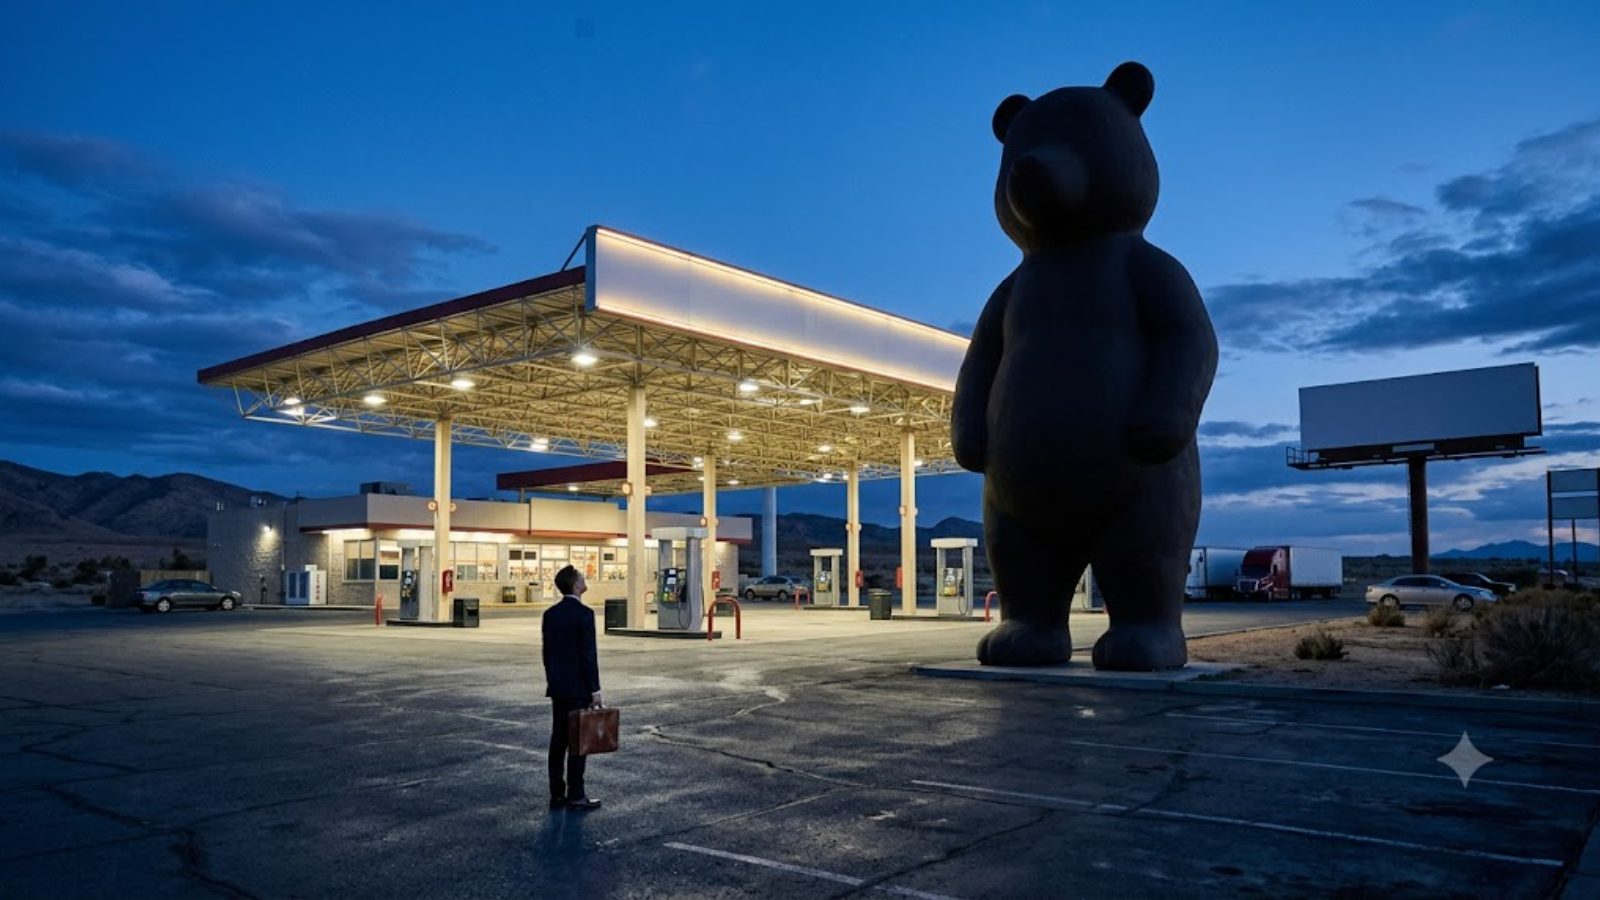
Buc-ee’s is suing a moose.
“A moose is not a beaver,” reply the moose’s lawyers. Under the gag is a real lesson. A brand worth defending is a moat worth paying for.
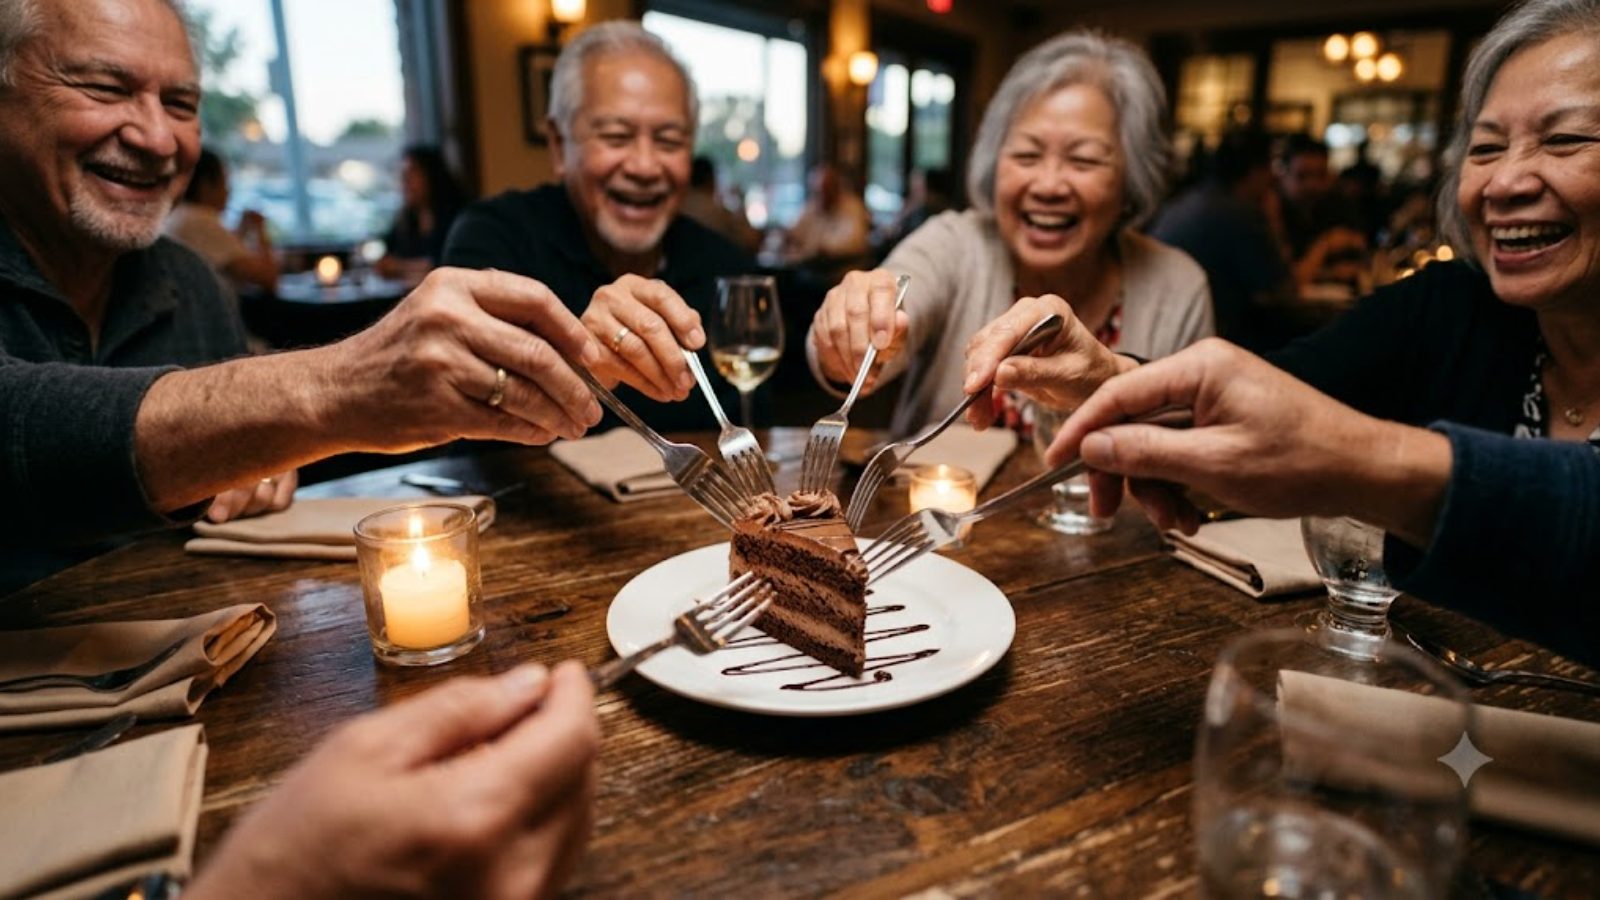
When your whole friend group turns 70.
Dinner at 6:00, one dessert, six forks, and a starting gun. Max Social Security if you waited, and the countdown to age-73 RMDs.
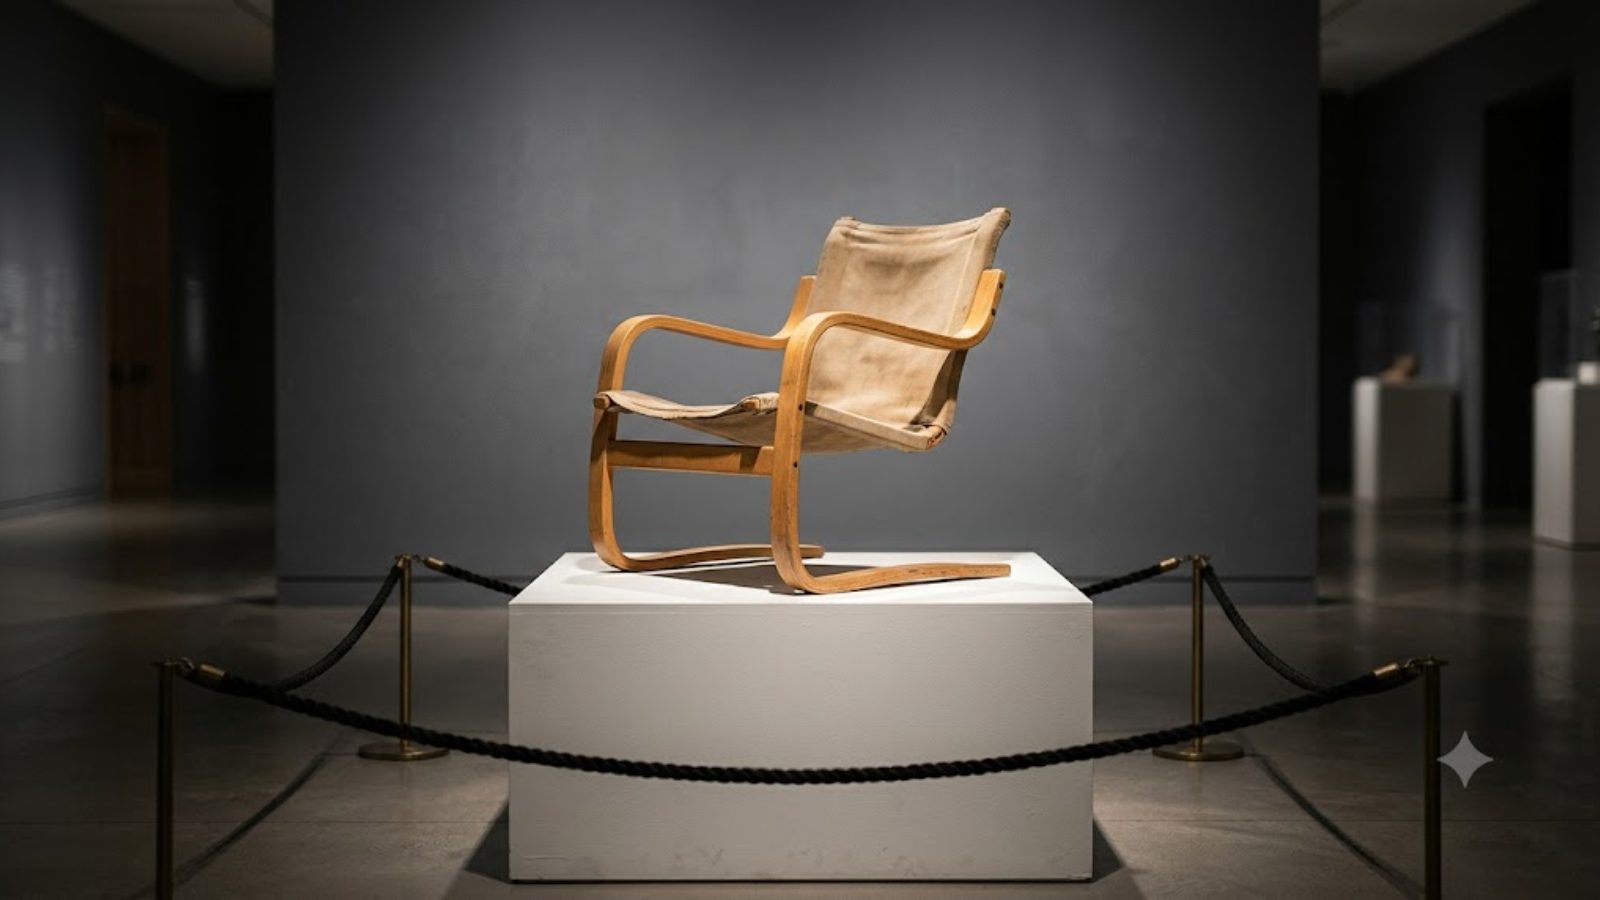
The $354 IKEA chair that’s worth $12,000 now.
Vintage flat-pack is an asset class now. It’s a great party fact and a terrible retirement plan.
From the desk Bias, the book, what’s priced, the planopen
Up and, finally, wide. Thursday wasn’t just a chip day. Russell 2000 +1.2%, KBW banks +1.9%, transports +2.1%, advancers over decliners 1,733 to 1,037, and the 10-year snapped a seven-day climb to 4.539%. When breadth, banks and trucks all confirm the record chase, you respect the market. You just refuse to pay stupid prices for it. Prediction markets still put 8% odds on a normal Hormuz by July 31. The peace trade gets our respect, not our insurance policy.
- DJIA52,487.41 +0.27%
- S&P7,543.64 +0.81%
- NASDAQ26,206.89 +1.30%
- RUT2,992.54 +1.22%
- SOX +3.06% (+83% YTD)
- 10Y4.539%
- WTI$72.08
- Gold$4,130.60
- VIX15.84
The AI trade re-picked its winners in a single week. Suppliers first, power always, dividends regardless. Own the sleeve, not the horse, and your income plan never depends on guessing which chip wins.