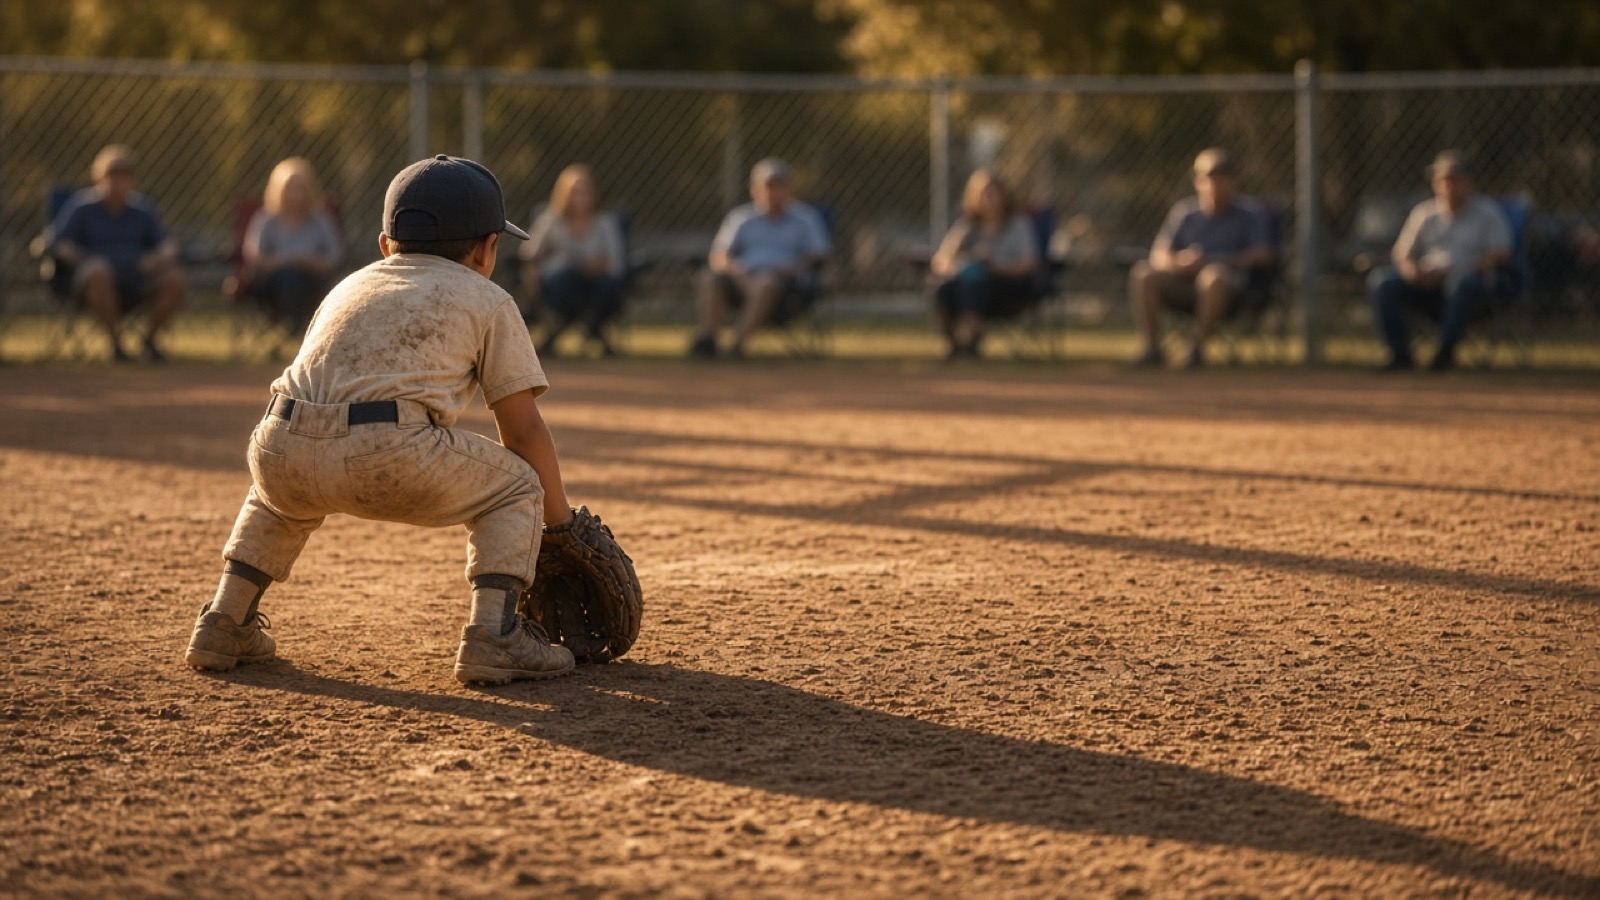
Picture a 3-foot-6 second baseman, a 44-pound shortstop, and bleachers full of parents who paid $60 apiece to watch them. That’s where Harriet Ryan’s Page One report in Tuesday’s Journal begins: a club tournament east of Los Angeles where the 6-year-olds were too young to pitch and the adults were spending thousands — including on a $191-a-year app selling advanced statistics on a first-grader’s at-bats. A $10,000 annual tab, Ryan writes, is common. The dad coach and the snack shack have given way to for-profit enterprises, some of them private-equity backed.
The money has gone up fast and up the income ladder. Average family spending on baseball rose more than 68% between 2019 and 2024 — from $660 to $1,113 a year, according to the Aspen Institute’s Project Play — an average that still includes Little Leaguers paying $110 to $170 a season. Serious families pay club fees up to $6,000, travel that can double or triple it, $500 bats, $400 gloves and $200-an-hour private coaches for 8-year-olds. The sorting shows up in the participation data: frequent play is down 28% since 2014 in families earning under $100,000 and up 21% above it. “It’s really a white-collar sport now,” says a Los Angeles club coach who runs a sliding scale to keep poorer kids on his roster.
Who’s selling? Youth sports is a $40 billion-a-year business. ZT Athletics, private-equity backed, has about 150 teams nationally and fielded three 6-and-under squads at that tournament. Perfect Game runs nearly 10,000 events a year and ranks children down to age 9. New York Empire Baseball took an investment from Shore Capital, a $17 billion Chicago firm. One Orange County mom says a family in her circle took a second mortgage rather than quit.
The investment parents think they’re making
Many parents say the point is a college career, and the base rates are brutal: less than 3% of high-school players will play Division I, and only about 5% of college players at any level are drafted. “They almost view it like an investment, and it’s a horrible investment,” says Bobby Minor, a baseball dad with a podcast. Not every family is chasing a scholarship. A Riverside County fire captain spends about $700 a month on a 6-year-old who can throw a bullet from short, buys used bats and skips out-of-state trips; a Catholic-school vice principal and her husband spend $2,000 to $6,000 a month on two boys, lean on family and credit cards, and ask the boys now and then, “Is this still fun for you?”
Our read
This is Cash Flow (M5) with a Time Value of Money (M3) problem hiding in it. Do the arithmetic Ryan’s parents mostly don’t: ten thousand dollars a year from age 6 through the end of high school is twelve seasons — a hundred and twenty thousand dollars before the money earns a cent. In a 529 plan it would have those twelve years to compound, tax-free for qualified college costs, against a bill that’s close to a certainty. The scholarship it’s meant to buy is a sub-3% shot. We’re not saying don’t play. The fire captain’s version — used bat, local park, no airfare — costs a fraction. We’re saying write the number down and decide it on purpose.
The tell in the story is the credit card and the second mortgage. A budget line that exists because the neighbors’ kid is at the tournament isn’t a plan, it’s a reaction, and private equity has priced it with care — fees by the month, contracts by the year, hotels by the night. Two rules for any family: no youth-sports spending on borrowed money, and the 529 contribution gets funded before the tournament fee, not after. If the question behind your season is a money question, that’s the fifteen minutes we’d spend with you. Better to check the forecast in spring than find out in the dugout.