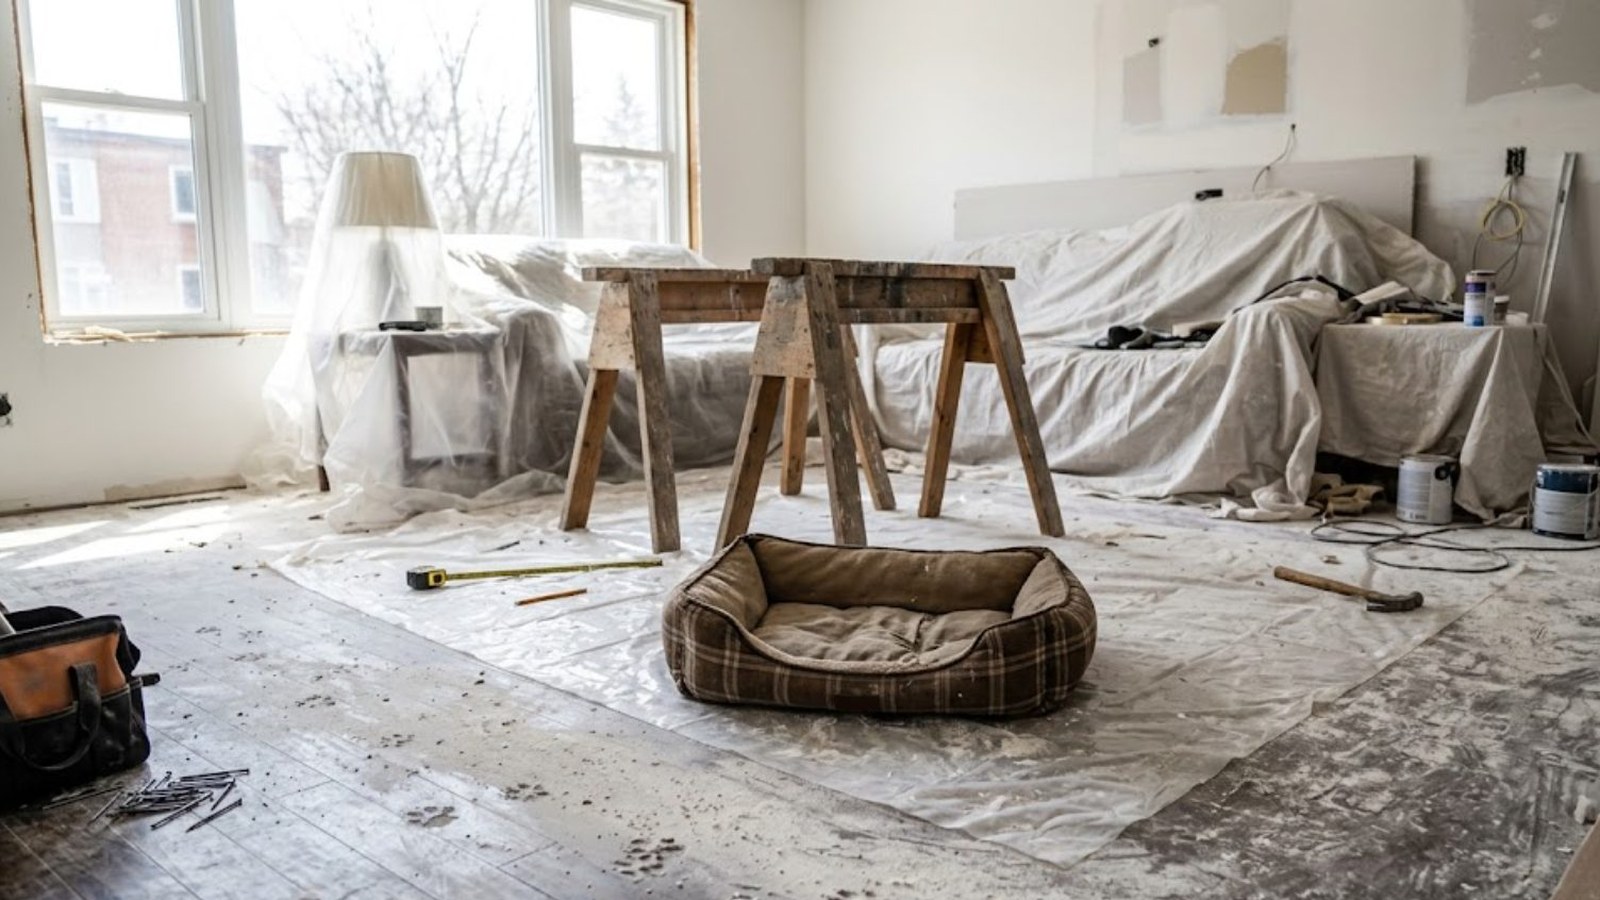
Raymond Porter bought an abandoned house in Orange Mound, Memphis, late last year for $79,000. Young people had been getting high in it. He put $20,000 into the place. Stolen copper wiring went back in, the moss came off the brick, dark red paint turned bright white, and the kitchen got a blue tile backsplash. Zillow says the value almost doubled. He rented it to a family for $1,400 a month, then borrowed $110,000 against it with a loan that looks at the rent, not the borrower's paycheck.
That loan is the story in Nicholas G. Miller's Property Report in Wednesday's Journal. It's a debt-service coverage ratio loan, or DSCR, born in the private-lending boom of the mid-2010s. A regular mortgage sizes up the borrower, with credit score, debt-to-income and assets. A DSCR loan sizes up the house, its value and the rent it can pull in. Many lenders don't even ask for proof of income. Tabitha Giddens, who fixed up a house in her native West Philadelphia, found it “way less paperwork.”
A safety net for flippers
The loan changed the math in neighborhoods banks had long avoided. In the 1930s the federal government marked East Cleveland, Ohio, “definitely declining” and warned banks off. Now, says Florida investor Ashleigh Wilson, somebody is working on a house on every street. She's never paid more than $24,000 for a Cleveland-area property. The money has also reached Indianapolis, Baltimore, Detroit and Memphis. A flipper who couldn't sell within 18 months used to face foreclosure. Now the flipper refinances into the 30-year DSCR loan and becomes a landlord, and in these neighborhoods renters outnumber buyers anyway. Baltimore has 30% fewer vacant buildings than in 2019, and its former housing commissioner, Michael Braverman, says private money did almost all of it.
Easy underwriting and lenders hungry for volume drew fraud. A group of New York investors is accused of borrowing against hundreds of vacant Baltimore houses last year at inflated values, pulling out cash and doing little or no work. Many of the loans went bad. A similar scheme came apart in Philadelphia this year. Lenders fled. Forecasa says Baltimore private lending is down 40% this year, and Philadelphia's fell 19% from a year earlier in the 90 days ended Sept. 11.
Our read
Housing M6 with an Insurance and Consumer Protection M11 warning label, and our verdict is watch. A loan that doesn't ask about your income isn't a favor. The lender has decided the house will pay for itself. If the tenant leaves or the roof goes, the payment still comes out of your paycheck, the one nobody checked. Porter's deal looks sound on the page because he bought at $79,000, spent $20,000 and rents for $1,400. The Baltimore scheme, as alleged, worked for a while because somebody wrote a value and a lender believed it. The difference was the underwriting the borrower did on himself. The paper doesn't print what these loans cost, and we won't guess, but a lender who skips your income is pricing something.
The connection to your plan is any rental you own or are weighing. This week's check is your own coverage ratio, by hand, meaning whether the rent covers the bills. Write the real rent, less one empty month a year. Subtract taxes, insurance, repairs and the loan payment. If that number is positive only when every month goes right, the house isn't paying for itself. You are. Do it before a lender who never asked about your paycheck says yes. The easiest loan to get is the one you most need to underwrite yourself, and nobody packs the umbrella for you.