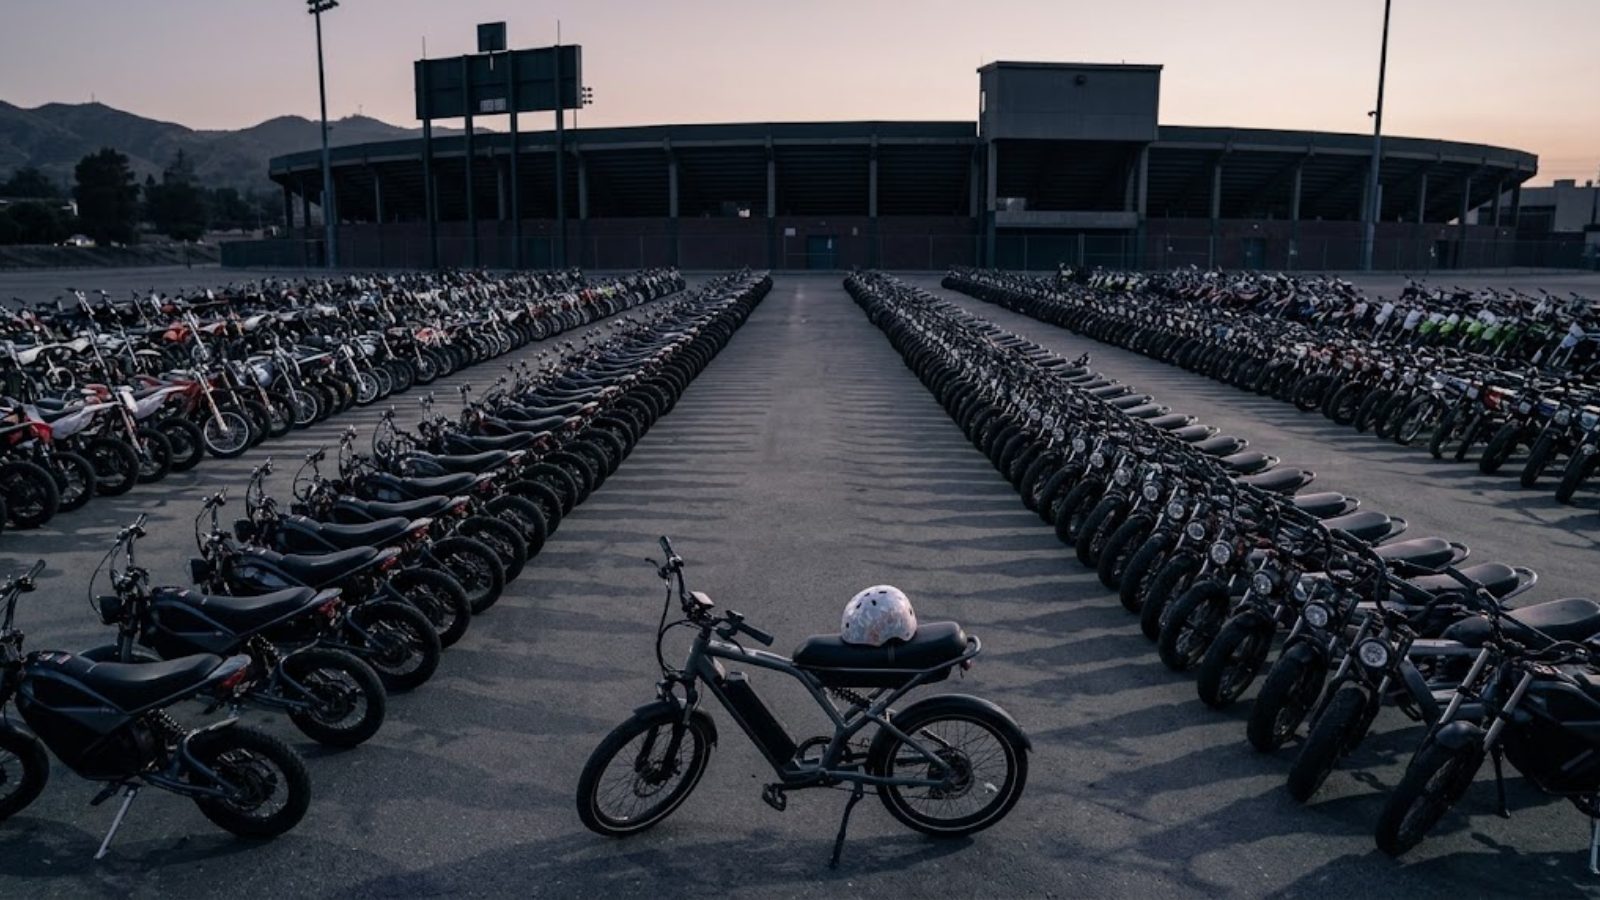
More Than 1,000 E-Bikes Turned In at Angel Stadium, and the DA Is Charging Parents, Too
Orange County’s district attorney traded gift cards worth up to $1,000 for more than 1,000 e-bikes and e-motorcycles in just over two hours, and he’s charging parents who allegedly let their kids ride illegally. For families, the question under both is whether they know what’s in the garage.
By Sean Anees Saifi · Capital Wealth · Published Friday, September 25, 2026 · Source: The Wall Street Journal, Friday, September 25, 2026 edition, whose market figures are the Thursday, September 24 close
Key Points
At a Sept. 13 buyback at Angel Stadium in Anaheim, thought to be the first of its kind, residents turned in more than 1,000 e-bikes and e-motorcycles in a little over two hours for gift cards worth up to $1,000, paid for with assets seized from criminals. Dozens were still waiting when the money ran out.
District Attorney Todd Spitzer formed an e-bike prosecution unit in May after an 81-year-old Vietnam veteran and substitute teacher was struck and killed, allegedly by a 14-year-old on an e-motorcycle. The teen’s mother faces felony child-endangerment and involuntary-manslaughter charges; her lawyer says she is anguished.
Spitzer’s office has charged at least three parents with child endangerment and is investigating 47 more. A lawyer for one charged father calls the prosecution absurd and blames how the machines are classified, marketed, sold and regulated.
Hospital patients treated for e-bike injuries rose more than 1,000% nationally between 2020 and 2024, according to a San Jose State University analysis. San Diego has banned riders under 12, a move local surgeons credit with fewer emergency-room visits.
The bike-or-motorcycle line is easy to miss: California’s e-bike classes top out at 28 mph, while faster e-motos require a driver’s license. One Anaheim father learned the e-bike he bought his son was an e-moto that could hit 45 mph.
1,000+
e-bikes and e-motos surrendered in about two hours
1,000%+
rise in U.S. e-bike injury patients, 2020–24
47
more parents under investigation by the DA
28 mph
top speed of California’s legal e-bike classes
California’s legal e-bikes top out at 28 mph. One Anaheim father found out his son’s could do 45.
In one line: An e-bike can legally be a bicycle or a motorcycle, and Orange County’s buyback and parent prosecutions show why families need to know which one is in the garage — for safety first, then for liability.
The first person turned up at Angel Stadium at midnight, and by dawn the queue had outgrown the parking lot. Nobody was there for baseball. They were rolling e-bikes, and the Orange County district attorney was promising to crush every one. On Sept. 13, it took just over two hours for residents to hand over more than 1,000 e-bikes and e-motorcycles in exchange for gift cards worth up to $1,000, paid for with assets seized from criminals. Some who were still in line when the cards ran out left their bikes anyway.
The buyback was modeled on gun buybacks and is believed to be the first of its kind, Friday’s Journal reports. It’s also the gentler half of District Attorney Todd Spitzer’s campaign. He formed a special e-bike prosecution unit in May, after Ed Ashman, an 81-year-old Vietnam veteran and substitute teacher, was struck and killed on foot after classes at El Toro High School — allegedly by a 14-year-old doing wheelies on an e-moto. The teen’s mother faces felony child-endangerment and involuntary-manslaughter charges; her lawyer says she’s anguished. The office has charged at least three parents and is investigating 47 more, and one charged father’s lawyer calls his client’s prosecution absurd.
The injury numbers explain the urgency: hospital patients treated for e-bike injuries rose more than 1,000% nationally between 2020 and 2024, a San Jose State University analysis found. Part of the problem is knowing what you bought. California’s three e-bike classes top out at 28 mph; beyond them sit e-motos, faster machines that require a driver’s license. Fred Sigala of Anaheim thought he’d bought his son an e-bike last year. It was really an e-moto capable of 45 mph — illegal for a boy his age — and the two rolled it through the stadium line to give it up.
The pressure on parents is social, too. Samantha Curtis, whose daughter asked for an e-bike in 2021 when the family lived in San Clemente, remembers that “if you didn’t have an e-bike, you basically didn’t have any friends.” Her daughter broke a collarbone and punctured a lung when the brakes on a borrowed e-bike failed. Ethan Carlos, 15, wasn’t allowed an e-bike at all; he died in January 2025 riding on the back of one — a bike a friend’s mother had let the boys ride — when a car struck them.
Our read
Start with the question that tripped up Fred Sigala: is it a bicycle or a motor vehicle? That answer decides whether — and where — a kid can legally ride, and it can decide whether your insurance shows up. Many homeowners policies limit or exclude liability for motorized vehicles, and insurers don’t all treat e-bikes the same way, so get the answer in writing. Then check the umbrella, too: it generally sits on top of your home and auto liability coverage and may not pick up what those policies exclude. It’s insurance planning (M11) at its least glamorous and most useful.
The Carlos family’s loss points to the harder corollary: your exposure may not stop with your own children. Depending on your state and your policy, it can reach the friend who borrows the bike in your driveway. And the charges in this story aren’t a coverage question at all; they’re about what a parent allowed. So set the household rules — who rides, where, how fast, and whether visiting kids ride at all — before anyone asks.
What It Means For Your Portfolio
Hold — insure the e-bike like the vehicle it is
No portfolio action — the position is in the garage: know whether the machine is legally a bicycle or a motorcycle, and know in writing whether your policies cover it.
General planning principles, not advice for anyone in particular. Liability is the risk families tend to think about last, because it arrives all at once. Before an e-bike joins the household, confirm its class and top speed and ask your home or renters insurer in writing how it’s treated. Don’t assume an umbrella fills the gap: it generally sits on top of your home and auto coverage and may not cover what those policies exclude, so check your policy.
Then write down the household rules and share them with the parents of your kids’ friends. It feels fussy right up until the day it isn’t — and fifteen minutes with the policy and the spec sheet costs far less than learning the difference the hard way.