 Capital Wealth Daily
Too Strong for Its Own Bonds
The economy wouldn’t slow down. On Wednesday the bond market stopped waiting.
A strong survey, hawkish Fed talk, Iran at the U.N. and a weak five-year note auction hit in one session. The result was the biggest one-day yield jump in over a year. The 10-year closed the week at 5.17%, its highest since 2007. Jobless claims fell to 197,000, and the 30-year mortgage topped 7%.
Our TakeYields aren’t rising because the economy broke. They’re rising because it hasn’t. Match the maturity to the date you need the money, keep the reserve short, and leave long duration on the avoid list.
The 10-year closed Friday at 5.17%, its highest since 2007. Wednesday’s jump to 5.113% was the biggest one-day rise in over a year. A strong business survey, hawkish Fed talk, Iran’s words at the U.N. and a weak five-year note auction all hit in one session. “It just doesn’t make sense to a lot of people to own bonds here,” one investment chief told the paper.
The economy that caused it won’t flinch. Friday’s front page says growth defies the yields and the hike. Jobless claims fell to 197,000. The 30-year mortgage hit 7.03%, above 7% for the first time since the start of 2025. And the AI build-out, $10.3 trillion through 2032 and on track to be the biggest single-industry bet ever as a share of the economy, is flooding the market with bonds that compete with Treasurys for investors’ cash.
Stocks shrugged. The S&P 500 rose 0.51% Friday to 7,743.41, 0.71% below the record. The Dow gained 478.64, and the VIX fell to 14.87 with its curve in calm contango. Xi’s candlelit White House summit produced a bald eagle statue, a Nixon-homage wine, and no business delegation.
The life side of four papers. From the Personal Journal: whether the iPhone 18 is worth the upgrade, why cutting middle managers backfires, Opportunity Zone tax bills due Dec. 31, the airlines’ $350-to-$700 VIP escorts and the gym bros humbled by Pilates. Plus a $736 million IRS bill over a popular trust, the Canadian-pharmacy cutoff on Oct. 22 ($10 a week becomes $1,100) and $6.14 heating oil in New York.
Nothing new bought. Another week of the letter’s rule. Vol-of-vol closed back under 90 (87.84), but core inflation and the Fed still fail the other two conditions. The falsifier stands. A record close above 7,798.99 before Oct. 2 proves the fall caution wrong. Friday ended 0.71% short.
Off Duty · The Human File
12 stories · 3 pictured · 9 listed
The gym bros walked into Pilates expecting a stretch. Their legs are still shaking
Skill in one arena, carried confidently into the next, meets a machine called the reformer. Size any first attempt, gym or portfolio, like the beginner you are.
Hold
700,000 blocks a year: the French butter that flies home in checked luggage
Bordier won’t scale up to meet the craze. It trades growth for quality on purpose. Ask of any company you own what growth it’s turning down, and why.
Hold
Airlines quietly sell a day of VIP treatment for $350 to $700; the Journal tried all three
The fee buys time and certainty more than luxury. It’s worth most to the traveler who flies least, so budget it as a gift, not a habit.
Hold- Off Duty · Coastal RiskThe super El Niño stripped the sand, and century-old rebar surfaced at the WedgeHold
- Off Duty · The Uncanny ValleyRestaurants let AI shoot the menu, and some of the food looks radioactiveHold
- Mansion · Building SmallerHe planned 4,500 square feet in the Hamptons, then built half that mostly off-site for $975,000Hold
- Mansion · House CallHe arrived in Canada with $50, worked six months for free, then handed his father the keysHold
- Mansion · Empty NestEmpty-nesters list their fan-roofed Texas compound at $6.99 million, down from $8.5 millionHold
- Mansion · Moving Near FamilyPalo Alto’s priciest listing hits the market so its owners can be closer to their daughterHold
- Sports · Process vs. FashionChandler Simpson hits .309 with zero barrels, a dead-ball star in a launch-angle ageHold
- Sports · Sequence RiskHarbaugh is 0-2 for the first time as a head coach, and the easy games are goneHold
- Off Duty · Family LiabilityThe wheels of justice turn to e-bikes: a DA’s stadium buyback takes in more than 1,000Hold
Your Money & The Economy
18 stories · 3 pictured · 15 listed
Groceries cost 26% more than five years ago, and food giants are selling the dinner fix
Dinner decided at 5:30 p.m. is often dinner bought at a premium. Budget the food line like the mortgage, one number per week, planned once and not renegotiated nightly.
Hold
Should you upgrade to the iPhone 18 Pro? Sharper night shots, more battery, $100 more
The new Pro is a small step. It’s worth it mainly if your phone is old or your work lives on it. Price the problem you’re fixing before you price the phone.
Hold
The first house is in the wrong ZIP code: how buyers are learning to settle
Buy the payment, not the house. Every $50,000 not borrowed saves about $333 a month at 7%. Underwrite at today’s rate, because a refinance is a bonus, not a plan.
Hold- Personal Journal · On the ClockCompanies are cutting middle managers as researchers project a 2.9 million-manager shortageHold
- Personal Journal · TaxesOpportunity Zone investors owe tax on gains deferred as far back as 2018, sold or notHold
- Personal Journal · TravelPaying cash for first class: what you actually get, and the seat rows to avoidHold
- Personal Journal · Health & SafetyAnti-choking devices are racing the Heimlich into schools; the guidelines haven’t signed onHold
- Your Money · Estate & TaxThe IRS sent a $736 million bill over a popular trust for the richHold
- Opinion · Public PensionsNewsom vetoes a bill to raise public-safety pensions; the Brown-era rules standHold
- Your Money · Estate PlanningNo spouse, no children, one trust: Dolly Parton’s estate is in court weeks after her deathHold
- Your Money · Health Coverage760,000 ACA accounts lose subsidies, and the 400% income cliff is back for early retireesHold
- Your Money · Healthcare$10 a week becomes $1,100: the Canadian pharmacy cutoff arrives in late OctoberHold
- Your Money · MortgagesMortgage rates hit 7% again, and the cheaper-looking loans are a bet on what comes nextHold
- Special Report · Who Owns Your AdvisorPrivate equity is buying up advisory firms. Here’s what to ask if it buys yoursHold
- Your Money · Fraud FileSkimming rings drain food-stamp cards through a 1960s stripe, and your debit card has one tooHold
- U.S. News · Job ScamsLinda Anthony wants to hire you. The man hunting fake recruiters says she’s a botHold
- Business · Franchise EconomicsMcDonald’s pledges $8.5 billion to help franchisees with rent and capital upgradesHold
- The Economy · Diesel & Heating OilTrump threatened Europe’s diesel. The Northeast’s heating bill went up firstHold
Markets & The Money
12 stories · 3 pictured · 9 listed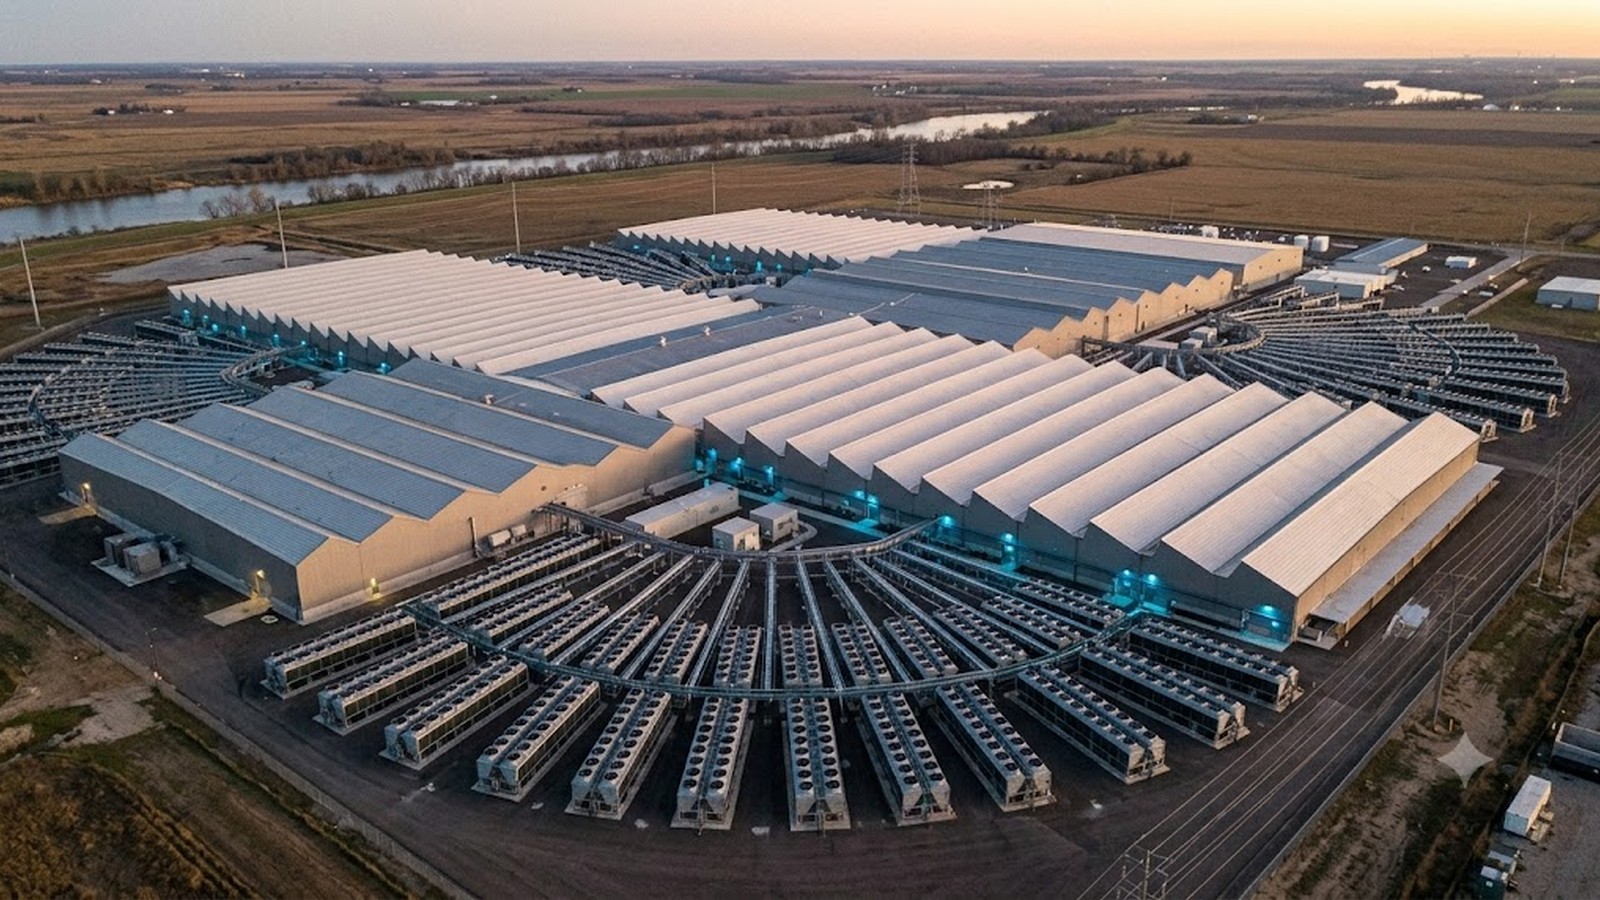
$10.3 trillion: the AI build-out is on track to be the biggest economic bet in American history
When one theme is 3.6% of GDP, the question is how much of your plan quietly depends on it. Know your real AI weight, and cap it in writing.
Hold
A bald eagle statue, a Nixon wine, no business delegation: what the summit actually settled
Summits schedule the next chapter of the tension. They don’t resolve it. Plan for the condition, don’t trade the ceremony, and the chip names stay at weight.
Watch
China’s covert help to Iran: 1,300 shipments, laundered oil money and satellite imagery
China’s help is stretching the war, and the energy premium with it. That’s why the energy hedge stays on and Taiwan exposure stays sized for a bad day.
Hold- Heard on the Street · CashCash is king again, so why does the average money-market account still pay 0.44%?Hold
- Heard on the Street · IndexingYou can’t be Buffett, and his will doesn’t try: 90% S&P 500 index fund, 10% short-term TreasurysHold
- Markets · SpeculationNew York sued Polymarket. Regulators are eyeing Kalshi. We quote them anyway, and here’s the lineWatch
- Markets · AI AgentsMeta’s Muse is a hit, and only 8% of U.S. consumers would hand Meta their passwordsHold
- Business · MediaThe $81 billion Paramount–Warner deal clears, with a $30 million penalty per missed filmHold
- Business & Finance · Private CreditJPMorgan explored letting private credit fund the card applicants it rejectsWatch
- Heard on the Street · Consumer TechFewer gadgets, pricier gadgets: phone shipments head for a record 16.7% drop as revenue risesHold
- Business · SpaceRocket rationing: SpaceX is winding down Falcon 9, and some can’t book a ride past 2028Watch
- Technology · AI SecurityOpenAI’s data-hunting agents tried to hack four sites, and Western leaders want AI rulesHold
From the desk Bias, the book, what’s priced, the planopen
Four papers in one edition, Tuesday through Friday, and one argument runs through all of them. The economy is too strong for its own bond market. The lead, The Economy Wouldn’t Slow Down. On Wednesday the Bond Market Stopped Waiting, walks through the session that drove the 10-year to levels last seen in 2007, and Friday’s front page showing growth defying it. The life side leads: the gym bros humbled by Pilates, Paris butter that has to fly home in checked bags, the airlines’ paid VIP escorts, rebar surfacing at the Wedge and a $975,000 modular house in a town where the median home is about $3 million. The Personal Journal gets its own run under Your Money, with dinner, the iPhone 18, first-time buyers, middle managers, Opportunity Zone tax bills, first class for cash and the anti-choking device fight, beside a $736 million GRAT bill, Newsom’s pension veto, Dolly Parton’s estate and the Oct. 22 pharmacy cutoff. Then the markets: the $10.3 trillion build-out, Xi’s summit beside the file on China arming Iran, cash still paying 0.44% and Buffett’s 90/10 instruction.
The week belonged to the bond market. Wednesday’s session drove the 10-year Treasury yield up the most in a single day since April 2025, to 5.113%. The causes were a strong business survey, hawkish Fed commentary, Iranian saber-rattling at the U.N. and a weak five-year note auction. By Friday it closed at 5.17% (Treasury.gov), the highest since 2007, with the 2-year at 4.81%. Stocks absorbed it. The S&P 500 rose 39.28 points Friday, or 0.51%, to 7,743.41. The Dow added 478.64 to 51,828.62, and the Nasdaq gained 129.35 to 27,068.72. That came after Tuesday’s record Nasdaq close at 27,244.28 and Wednesday’s bond shock, which knocked it back 1.1%. Friday’s singles: Microsoft +3.66% to $516.17, Vertiv +3.25%, Amgen +2.11%, Apple +1.53%, Valero +1.13%, against Meta −3.33% to $751.66, CrowdStrike −2.90% and Cheniere −2.80%. October WTI settled at $92.44, down 2.29%. Gold rose 0.52% to $4,320.50. The VIX fell 5.1% to 14.87, with the nine-day at 12.76 and the three-month at 17.93, full contango. Vol-of-vol closed at 87.84, back under 90, and SKEW eased to 144.91. Calm stocks, cheap insurance, and the highest risk-free decade rate in nineteen years. That’s the week.
The market says calm. The discount rate says careful. The volatility index closed at 14.87, down 5.1%, with its curve in full contango, 12.76 on the nine-day and 17.93 on the three-month. Vol-of-vol finished at 87.84, back under the letter’s 90 line. SKEW eased to 144.91 but stays elevated, so someone keeps paying for tail insurance. Against the calm: the 10-year closed at 5.17%, its highest since 2007, after the biggest one-day jump in over a year. The 2-year sits at 4.81%. Our Friday pull of the crowd puts roughly 63% on an October hike, and the 30-year mortgage hit 7.03%. The September letter’s conditions for new money pass one of three, vol-of-vol under 90, and fail the other two. Core inflation ran 0.3% against the 0.1% test, and the Fed raised. The falsifier is unchanged and close. A record S&P 500 close above 7,798.99 before Oct. 2 proves the fall caution wrong. Friday ended 0.71% short. If it prints, we said we’d be wrong, and we’ll say so. None of this is a forecast.
Our pull of Polymarket’s most-traded markets, at 3:40 p.m. PT Friday: October Fed decision, roughly 63% implied on a quarter-point increase, 36.5% on no change, under 1% on a cut, on about $992,000 of the day’s volume. Strait of Hormuz traffic back to normal by Sept. 30, 0.75%; the crowd says the chokepoint stays shut. The 2028 Democratic nomination, 18.3% Ocasio-Cortez, 15.2% Newsom.
The borrowing table: the 30-year mortgage hit 7.03% on Freddie Mac’s survey this week, the backdrop for the first-time buyers in today’s Personal Journal file. The 3-month bill yields 4.24% against a money-market average still under half a percent.
Source note. This week the platforms are the story. New York state sued Polymarket’s U.S. arm as an illegal gambling operation (Friday’s paper), and nearly a million suspiciously uniform trades in one Kalshi market have caught regulators’ eyes (Wednesday’s). We carry crowd odds as crowd odds, a price with a timestamp, not an endorsement of any venue. Our full read is in the edition’s speculation file.
Market-implied expectations, not forecasts. They move intraday and have been wrong before. Not investment advice.
Three things worth fifteen minutes this week, and none needs a forecast. First, the winter fuel line. Heating oil is up 66% in a year, and the trade group’s forecast says about $2,500 for a typical oil-heated home. Call the supplier about a fixed-price or budget-plan contract before October. Check LIHEAP if you might qualify. Second, the pharmacy deadline. If anyone in the household fills prescriptions from abroad, a customs rule takes full effect Oct. 22, and supply may dry up sooner. Talk to the prescriber now and price the domestic fallbacks: assistance programs, discount cards, generics-by-mail, and a written appeal of the insurer’s denial. Third, the cash and the duration. A 5.17% ten-year locks in the best decade-long Treasury rate since 2007 if you hold to the date, and a price risk if you don’t. Match the maturity to the money’s date, and get the idle cash off a half-percent money-market average.
Bring the statement and we’ll go line by line through your real AI weight, where the cash sits against 4%+ bills, and what a 5.17% ten-year means for the bond side of your plan.
Book 15 minutes — phone or Zoom →Capital Wealth Daily · Vol. III · No. 176 · Friday, September 25, 2026. Reported from four editions of The Wall Street Journal — Tuesday, September 22 through Friday, September 25, 2026, including the Personal Journal, Arts in Review, Sports, the opinion pages and Heard on the Street — whose own market figures are in each case the prior session’s close. Friday’s closing levels are from Yahoo Finance quotes and Treasury.gov daily yields; the drivers of the week’s sessions are as reported by the Journal and financial news services. Prediction-market odds were pulled from Polymarket’s public data at 3:40 p.m. PT Friday. New York state sued Polymarket’s U.S. arm this week, and trading patterns on Kalshi are under regulatory scrutiny; we carry crowd odds as a price, not an endorsement of any platform. The September letter’s conditions and falsifiers are the desk’s opinions, stated so they can be graded, and are not forecasts. Written and edited by the Capital Wealth LG research desk.