 Capital Wealth Daily
The Hike Issue
Our read of the July 9 Wall Street Journal (Wednesday, July 8 close). Every story with its tickers, and what the model books did about it.
Nine of eighteen Fed officials penciled in a hike. We penciled in getting paid either way.
The first Warsh-era minutes said the quiet part out loud. Now nine of eighteen officials see at least one hike by December, up from zero in March. Futures priced 80%+ odds. The 10-year hit 4.567%. The Dow gave back 577 points on American Express (AXP), Sherwin-Williams (SHW) and Boeing (BA). Nvidia (NVDA) rose 3.7% to $204.12 anyway, with Vertiv (VRT) at $317.81 and Constellation (CEG) at $244.52. The committee’s new inflation culprit is the debt-financed AI build-out itself. It named Amazon (AMZN) and Oracle (ORCL) as the borrowers who don’t flinch.
Our ReadSGOV reinforced across every tier. The bill ladder and the 0.5% cash buffer keep collecting 4%+ while the committee argues toward July 28. IAU held. Inflation at 4% is exactly what it’s there for, even on a $74 down day. Long duration stays avoided. A 10-year at 4.567% under a hawkish committee is a promise we don’t need. We don’t rotate a portfolio on one set of minutes. We do stop reaching. And if you’re CalSTRS or CalPERS, your pension already does the duration work. Your portfolio doesn’t have to.
The Stories
6 stories · 3 pictured · 3 listed
Hormuz traffic “essentially stopped.” Our energy insurance just earned its premium again.
Chevron (CVX), Exxon (XOM) and ConocoPhillips (COP) stay reinforced. The toll-takers behind them, Kinder Morgan (KMI), Williams (WMB) and Texas Pacific Land (TPL), keep collecting whether the strait opens Tuesday or Christmas. MPC and VLO go on the watch bench, with respect. Buying a refiner at a 52-week high on war news is like buying a beach house during the hurricane. Spike days are for rebalancing into the plan, not out of it.
Apple handed Broadcom $30 billion. We already owned the guy getting paid.
AVGO reinforced. A signed, multi-year Apple commitment is revenue you can underwrite, and that is the whole test. TSM reinforced with it. The foundry gets paid on every one of those 15 billion chips. Goldman Sachs (GS) goes into the tactical book at 1% next to JPM and MS. A record deal wave is a fee wave, and we’d rather own the toll booth than admire the traffic.
The memory trade looks absurdly cheap. That’s exactly why we’re only watching.
MU stays on the watch bench, and we watch Friday’s SK Hynix debut from the stands. The trigger to upgrade is a contract we can underwrite. That means a signed multi-year buyer, U.S.-plan money, something you can take to a committee. Until then, our memory exposure rides inside the sleeve we already own. AVGO, TSM and NVDA get paid whichever memory maker wins the food fight.
Off Duty & The Life File
4 stories · 3 pictured · 1 listed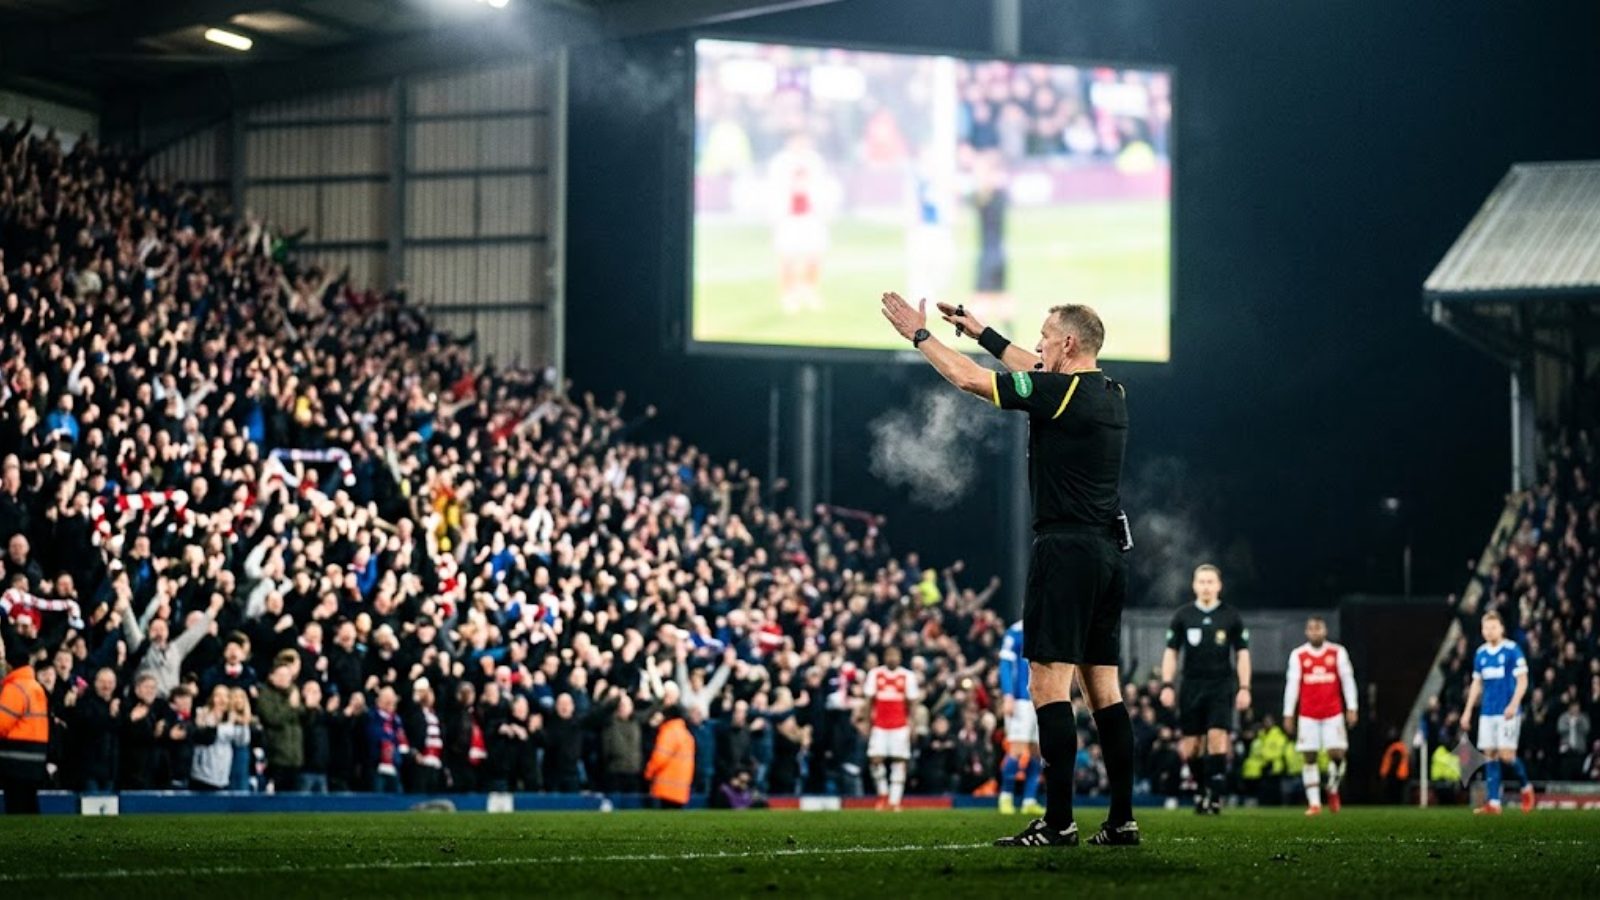
Destroy the replay booth: VAR is ruining the World Cup.
Messi cried after missing his penalty. Then Argentina scored three in thirteen minutes. Endless re-review ruins the beautiful game, and it quietly ruins portfolios too.
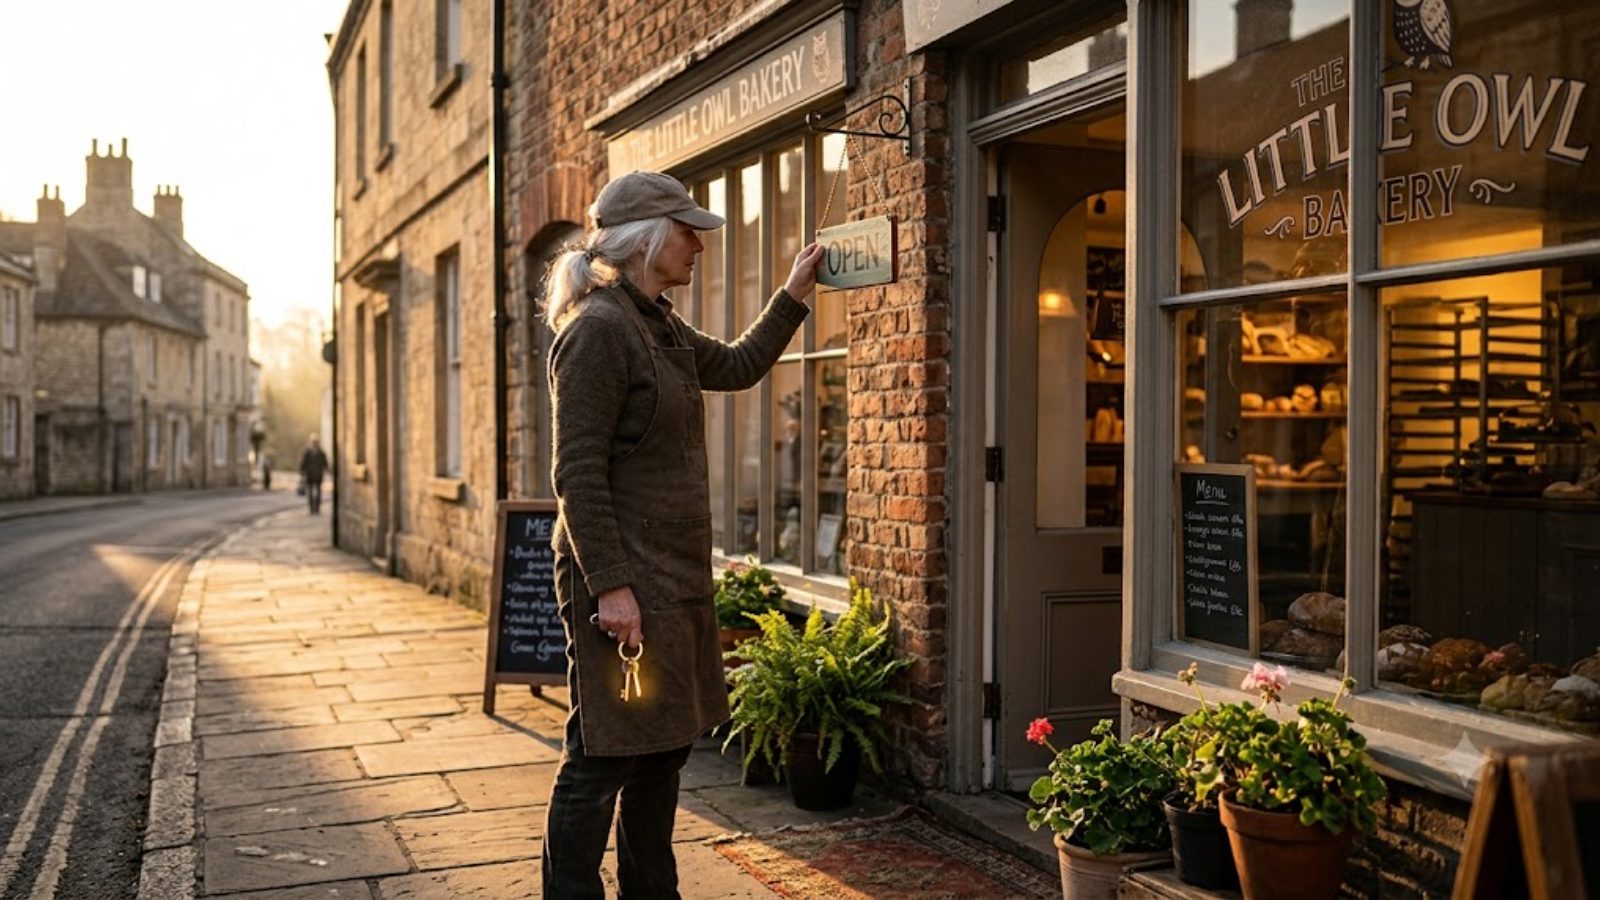
They retired. Then they opened the business.
Incorporations by 55-to-64-year-olds are up 22% in a decade. We have two rules. Risk the 10% you could laugh off losing, and wall off the rest.
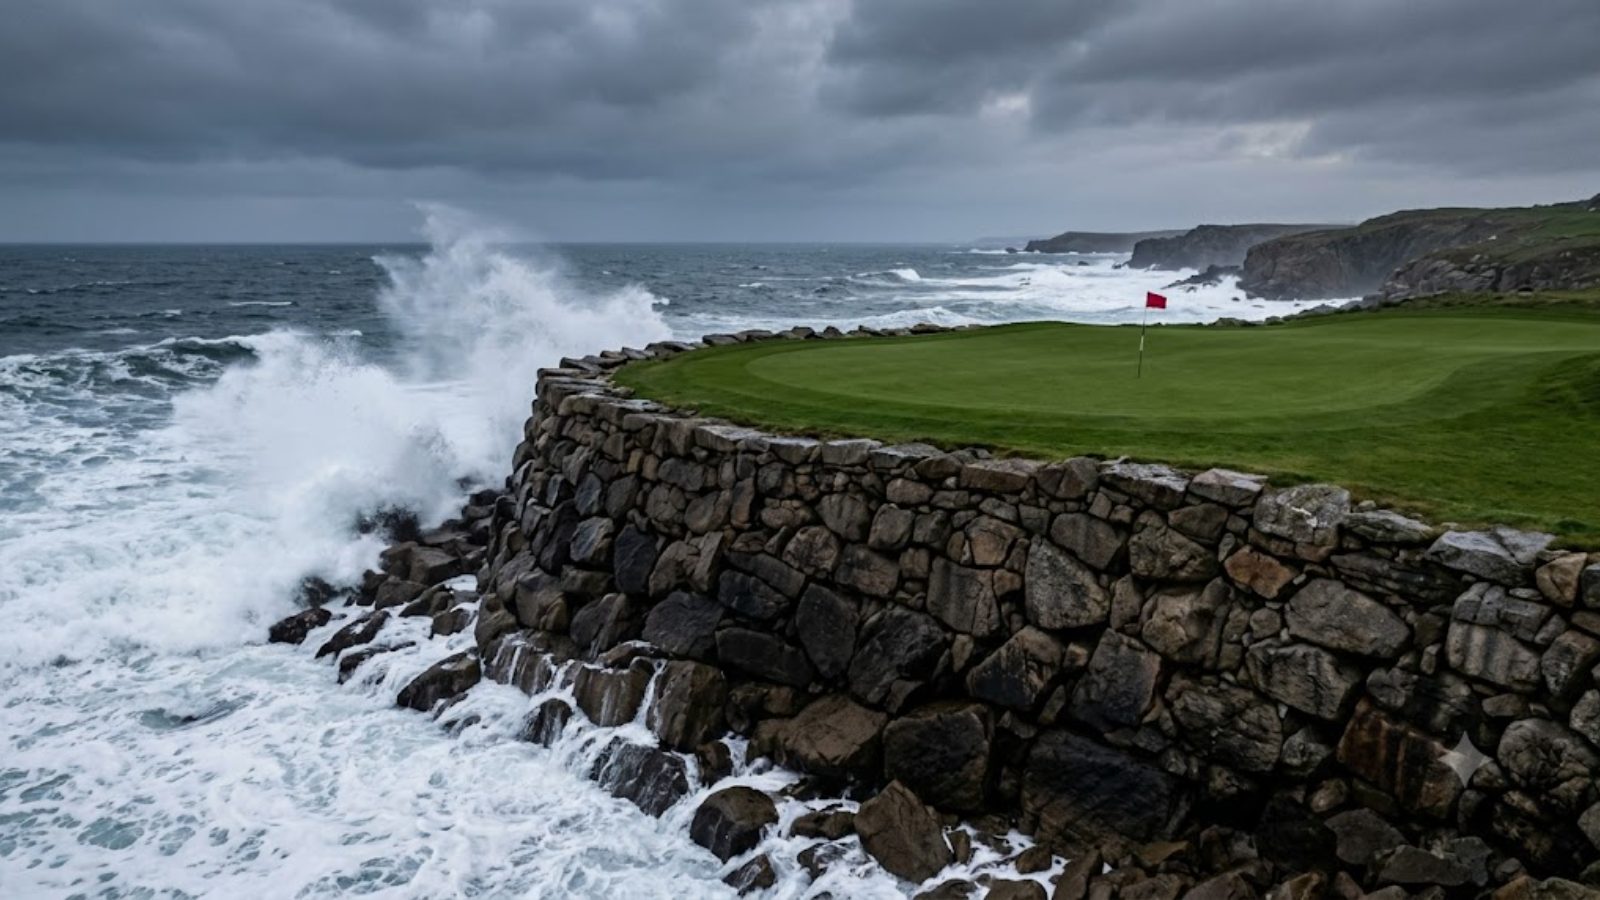
A golf club built a secret 20-foot seawall. Rhode Island noticed.
Two football fields long, zero permits, hedging a storm nobody could see yet. The instinct was right. The paperwork, less so.
From the desk Bias, the book, what’s priced, the planopen
Chop with an upward lean, and don’t trust the Dow to tell you the story. Wednesday was a split screen. Dow −1.1% on rate fear, Nasdaq up 0.2% because the AI complex shrugged. With futures at 80%+ for a hike, the market is done pricing rescue and has started pricing endurance. Whoever doesn’t need cheap money wins. We lean into short bills, the energy sleeve and suppliers with signed contracts. We trim long duration, managed care and anything at a 52-week high on a war headline.
- DJIA52,348.39 −1.09%
- S&P7,482.71 −0.28%
- NASDAQ25,870.65 +0.20%
- 10Y4.567%
- 2Y4.200%
- WTI$73.52
- Brent$78.02
- Gold$4,070.90
- VIX16.90
Hike or hold, the bills pay 4%+, the energy sleeve hedges the strait, and the suppliers cash Apple’s check. The plan doesn’t need the committee to decide. Lock the 2027–29 income while the window is open.