 Capital Wealth Daily
Three Dissents and a Thousand Points.
Part II is the macro half of the July 29–30 Wall Street Journal. It covers the Fed meeting that moved the Dow four figures, the war that moved oil twice, and the quiet pages about your retirement account that will outlast both.
The Fed stood still, and the floor moved.
The Fed held rates at 3.50%–3.75% on a 9–3 vote. For the first time since 2016, all three dissents pointed the same way, UP. Hammack, Kashkari and Logan wanted a hike, with inflation above target for a fifth year. Chairman Warsh has spent his first months saying less on purpose. He told markets he has no magic wand. The Dow gave up 1,153 points, its worst day of the summer. Traders decided “no cut soon” was the real statement.
Our ReadRead the dissents, not the decision. Three of the twelve voters wanted a hike now. About half of all Fed officials had already said one could be warranted this year. The market spent 2026 positioned for the next move to be down. On Wednesday it met a committee arguing the next move is up. Action: REINFORCE the defensive tilt and the short-term bill ladder, and AVOID adding long-term bonds while the committee debates hikes.
Off Duty · The Human File
3 stories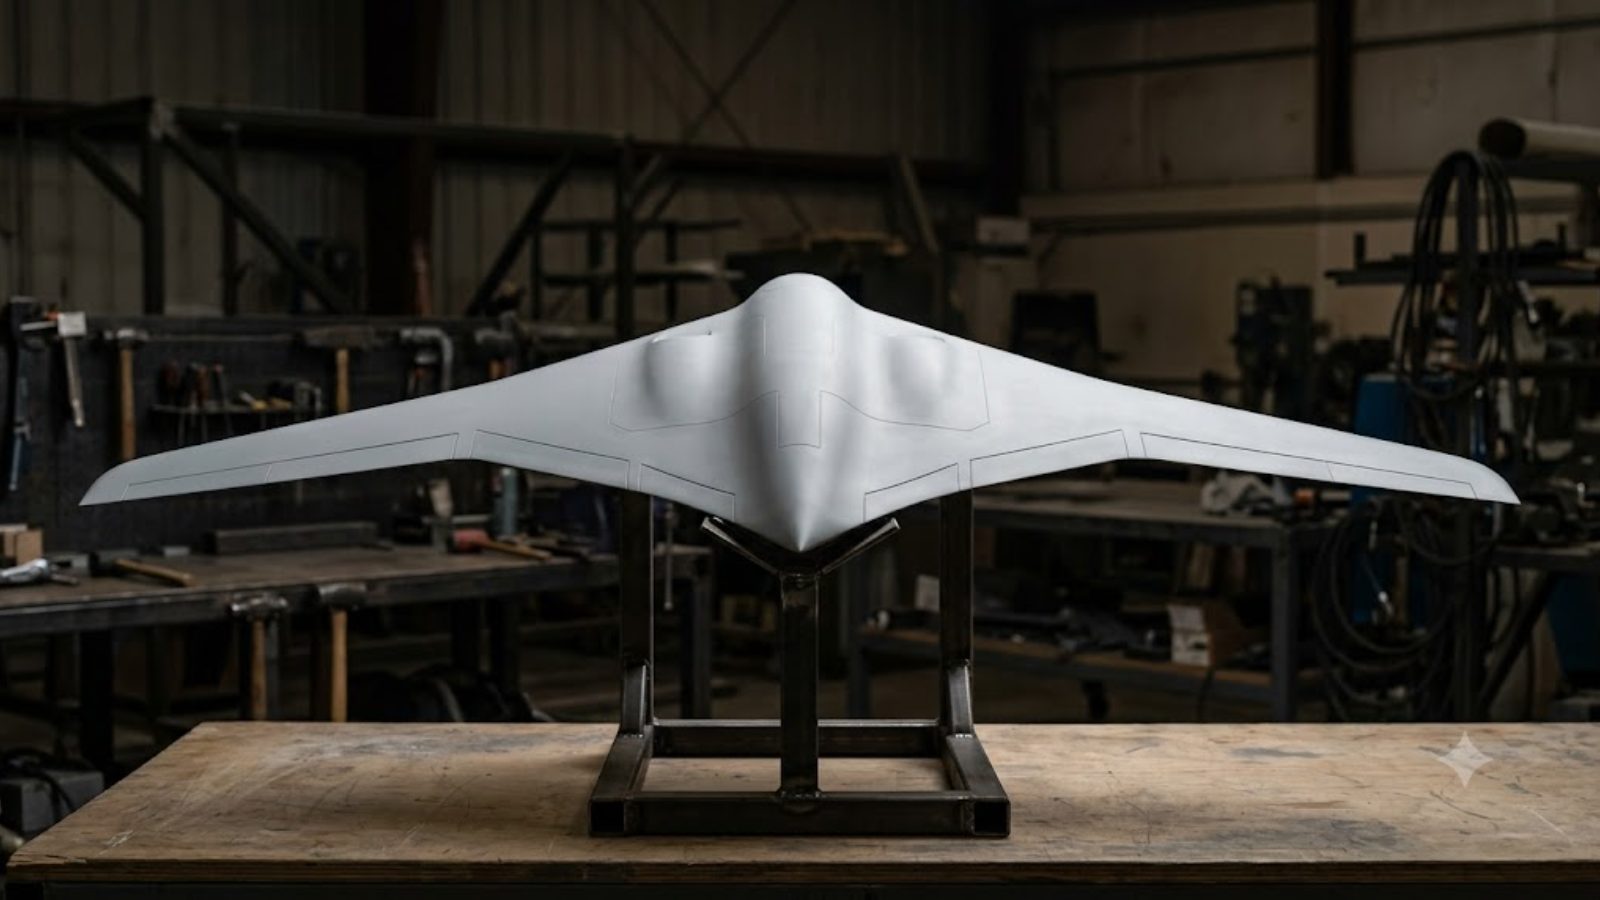
A manta ray is coming for Boeing.
Governments have decided a two-company airliner market is a strategic risk, so they are funding the challenger directly, just like they did with chips.
The consumer kept swiping through all of it.
Visa is the book’s cleanest way to own employed America, a toll on every dollar spent, with no inventory and no credit risk.
P&G just handed us the oil hedge’s receipt.
This is the receipt for the defensive tilt, where P&G pays $90 Brent and the energy sleeve collects it.
Your Money & Health
3 stories
The $20.6 million 401(k) was legal the whole time.
This is the page most likely to change a client’s life this week, and most people never asked the five-minute HR question that unlocks it.
The subsidy propping up Medicare drug plans is going away.
Health care is the retirement plan’s silent second mortgage, and the rate just went up, so re-shop Part D this fall and don’t renew by default.
The miracle drug is now a line item on your Medicare bill.
Same drug class, same calendar, sixteen points apart, with Lilly up 14.3% and Novo down 2.2%. That is a franchise war with a winner.
Markets & The Macro
6 stories · 3 pictured · 3 listed
Our oil thesis just ran a live-fire drill.
A $10 round trip is our floor-and-ceiling thesis tested in public, and the energy sleeve was the book’s only natural hedge on the worst day of the summer.
Meta asked Wall Street to pick up the AI tab.
The pair trade inside the megacaps is finally visible, sellers of AI with subscribers against spenders on AI with invoices.
The Pentagon just placed a $120 billion restock order.
A war that empties the magazine is a multi-year revenue commitment to whoever refills it, and this one is funded by an appropriation, not a bond deal.
Off Duty & The Life File
8 stories · 3 pictured · 5 listed
Parsons, Kansas may bury a nuclear reactor a mile underground.
Deep Fission’s “Gravity Reactor,” from Liz Muller and her Berkeley-physicist father, would heat water a mile down in billion-year-old granite. It has split a farming town of 9,600 between jobs-and-data-centers and I-can’t-think-of-a-worse-idea. The real limit on the nuclear comeback is the county commission, not the physics. Our uranium-and-utilities exposure stays index-shaped while the siting fights play out.
855 CEOs, twenty years, one lesson.
A study of the full tenures of 855 S&P 500 chief executives finds the market’s verdict is mostly written early. First-time CEOs outperformed more often than experienced ones. We hold positions longer than the average CEO’s honeymoon. Buy governance, not personalities.
Elon Musk’s tunnel company is worth $20 billion now.
The Boring Company is in talks to raise around $4 billion at a valuation near $20 billion, up from about $5.7 billion in 2022. Many of the city projects it pitched never panned out. Private-market prices are a mood gauge, not a valuation. The lesson is that late-stage money is still easy to find for anything close to one particular surname.
- Washington · The Hearing FileFauci took the Fifth.
- Life · The Aging-In-Place FileThe most dangerous room in the house.
- World · The Demographics FilePoor countries are aging fast, and can’t afford it.
- Off Duty · The Points FileThe flashy travel card, audited.
- Opinion · The Classroom FileAn op-ed our teacher clients will be talking about.
From the desk Bias, the book, what’s priced, the planopen
Part II is the macro half. A Fed arguing about hikes met a war that will not stay priced. The Dow paid 1,153 points to learn the difference between “rates on hold” and “help is coming.” The week’s sharpest analysis came from Heard on the Street, a desk we will carry in every edition from now on. China’s oil demand flexed 40% during the Hormuz closure. That softens the ceiling on crude even while the war holds up the floor. Our direction into August is unchanged and now battle-tested. A defensive core (P&G just showed you its $1 billion war invoice, and the same book owns the Chevron that collects it). Energy as the hedge that actually hedged. Aerospace on an appropriations floor. And the bill ladder earning 4%-plus while long bonds argue with the dissenters. The quiet pages mattered more. A $20.6 million 401(k) guide and a Medicare subsidy sunset will outlive every headline above them.
- DJIA51,594.14 −2.19% (−1,153.18)
- NASDAQ24,442.94 −1.7%
- STOXX600 645.01 −0.3%
- 10Y4.621%
- OIL$84.46 +$5.20
- GOLD$4,034.70 −$1.60
Two planning triggers this week. After-tax 401(k) contributions (mega-backdoor eligibility), and Part D re-shopping at open enrollment, October 15.