 Capital Wealth Daily
The 10-Year Turned Back 24 Years.
The 10-year just hit a 24-year high. The long end isn’t waiting on the Fed.
The Journal’s 10-year Treasury closed Wednesday at 5.292%. That’s past 2007 and back to 2002. Bills eased after a New York Fed official saw no urgency. The long end climbed anyway. Safe money stays in bills and floating-rate paper.
Our TakeThe long end is a term-premium story now, not a Fed-hike story. Bills and floating-rate paper stay the parking spot, and long duration stays avoided.
The 10-year closed at a 24-year high. The Journal’s yield was 5.292% Wednesday, past the 2007 peak. Treasury.gov put it at 5.29%. The 20-year sits at 5.68%, above the 30-year at 5.64%. Long duration stays avoided.
The fall falsifier did not print. A record S&P close above 7,798.99 before Oct. 2 never arrived. The closest was Sept. 25 at 7,743.41. The quarter ended 1.89% short at 7,651.54.
Q3’s rally was four stocks. S&P +2%, Nasdaq +2.5%, Dow −2.7%. Microsoft, Meta, Nvidia and Apple each rose 10% or more. Equal-weight S&P −2.3%. Narrow leadership, not a broad bid.
VLO’s trim is still unpublished. We added Valero Sept. 28 at 1.5%. We trim only when the White House publishes a diesel-export restriction. Heard named the idea. Nothing has been ordered. Watch, don’t trim.
The crowd flipped to a hold. At 8:16 a.m. PT Thursday, prediction markets priced 66.5% on no October Fed change. Sunday it was ~64.5% on a hike. That’s a crowd price, not a forecast. New York has sued Polymarket’s U.S. arm.
Off Duty · The Human File
12 stories · 3 pictured · 9 listed
We’re all starting to talk like chatbots. One office built a swear jar
The tool you type into starts talking back through you. When a money sentence feels too smooth, put a number under it.
Hold
Ford’s employee of the month is a hawk named El Charro
The cheap scarecrow isn’t a hedge. The one that works is the one that has to ride every day.
Hold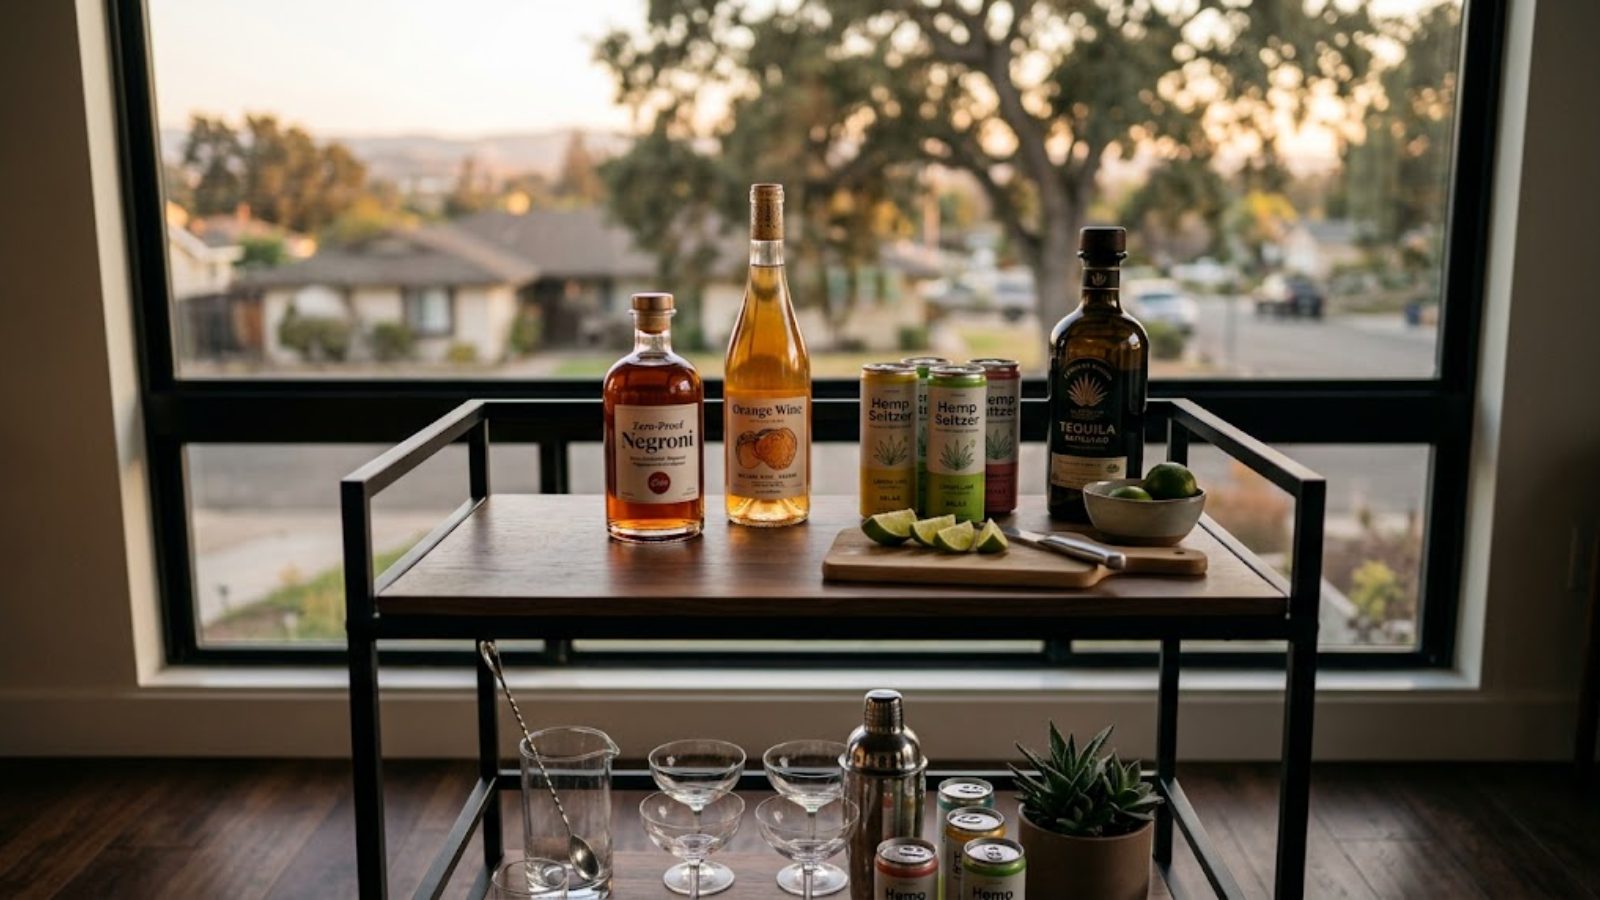
Lidl couldn’t get a wine license. So it opened a pub in the aisle
A $159,000 permit is a nest egg, not a drink. When the front door is locked, budget the side door that actually posts.
Hold- Page One · A-hedThe hottest playground in New York is a junkyard. Parents sign a waiverHold
- Page One · Human FileFlight 1073 lost 15,000 feet in 55 seconds. Passengers had to take the cockpit backHold
- Page One · BusinessEndless sirloin only works if you watch the trash can and the diesel billHold
- Page One · A-hedThey tried to make Monopoly in America. The premium was 100%, not 20%Hold
- Sports · Off DutyMarried in July, fastest since 2022. The Kelce rebuild at 36Hold
- Sports · Off DutyThe worst playoff team ever just taught a finance classHold
- Business · The Human FileUber will book you a lion. Finding a driver is harderWatch
- Business · Off Duty“Stairway to Heaven” is legal again at Guitar CenterHold
- Personal Journal · The Human FileTwo brothers, fifteen years, one held-open handHold
Your Money & The Economy
20 stories · 3 pictured · 17 listed
Social Security will pay your kids, if you file while they’re still young enough
The child’s months and the parent’s lifetime check are the same decision. Run both paths before anyone files.
Hold
Use it or lose it: the $860 Rome night that became $210
A credit you don’t use is just a higher fee. Count it against trips you were already taking, and book the portal that actually posts.
Hold
The wedding registry is now a down payment. Bring the gift letter
Wording is etiquette. Letting the gift sit is underwriting. A gift that isn’t documented is just a delay.
Hold- Personal Journal · HealthFlu climbed the death chart. The federal push to get the shot is shrinkingHold
- Personal Journal · Work & FamilyYour next raise may be whatever the model says you’re worthHold
- Personal Journal · HealthShe’s 5-foot-11, 138 pounds, and taking a GLP-1 for endometriosis painWatch
- Personal Journal · WorkCall it a check-in. Don’t call it a review. Gen Z still doesn’t know what’s expectedHold
- Personal Journal · WorkAdam Grant: the career edge used to be knowing more. Now it’s changing fasterHold
- U.S. News · Child AccountsTreasury will auto-enroll tens of millions of kids. The $1,000 still isn’t automaticHold
- U.S. News · EstateA $29 billion restaurant-supply sale is about to become a family officeHold
- U.S. News · MedicareMedicare will pilot matching 19 countries’ drug prices. It starts narrowWatch
- U.S. News · HealthLilly’s next shot, stacked on Zepbound, took off 23.3% of body weightHold
- Personal Journal · MoneyThe hot card now costs $325, because the premium ones hit $895Hold
- Personal Journal · HealthYour lab results now beat your doctor to the phoneHold
- Personal Journal · HealthThe $499 body scan wants your HSA dollarsHold
- Health Costs · Your MoneyA $500 check for ACA buyers. A rebate, not a raiseWatch
- The Economy · The QuarterThe quarter the economy stopped slowing downHold
- Property · The Human FileA town turned down $10,000 a householdHold
- Tax · Your MoneyTreasury fires the first shot at the disappearing gainAvoid
- Banking · Your MoneyThe bots just found your laziness taxHold
Markets & The Money
9 stories · 3 pictured · 6 listed
Q3 belonged to four stocks. The average stock lost, and the falsifier never printed
Narrow leadership is not a broad rally. The record close the desk named never printed, and we bought nothing new except the Monday Valero add.
Watch
China could cool diesel. A U.S. export ban would not
An idea in a column is not a published order. Valero stays at the Monday weight until a diesel-export restriction is written down.
Watch
Heard asks if bonds get a second chance. The 10-year closed at 5.292%
A higher coupon is not a reason to reload long duration. Bills stay the parking spot, and the Aggregate stays avoided.
Avoid- Markets · EquitiesNvidia’s $235 billion buyback authorization is not a $235 billion giftHold
- Markets · RegulationThe SEC just made it easier for ordinary investors to buy private funds. That is the pitchWatch
- Business · SuccessionGoldman has talked about Solomon handing the firm to Waldron as soon as next yearHold
- Markets · VoicesSix pros, one 5% ten-year, and one accidental consensusHold
- Heard on the Street · BondsPaid to be wrong: the quiet case for the two-year noteHold
- Insurance · Your MoneyAn annuity is a promise from a portfolio you’ve never seenWatch
From the desk Bias, the book, what’s priced, the planopen
Four weekday Journals, and a quarter that ended with the 10-year at a 24-year high. The lead, The 10-Year Just Printed a 24-Year High. The Long End Isn’t Waiting on the Fed, explains why long duration stays avoided. Bills eased on a dovish Fed comment. The long end did not. Then come the quarter’s four-stock rally; a China diesel-export idea that is not an order (Valero stays); Nvidia’s $235 billion buyback authorization, which is not an add; and the SEC opening private funds to more kitchens. The life side: Social Security for a retiree’s kids, hotel credits that expire, a wedding fund that can wreck a down payment, flu shots going quiet, AI setting the raise, GLP-1s off-label, Treasury auto-enrolling 60 million children, and a $29 billion restaurant-supply sale becoming a family office. Fun first: prompt-speak, a Ford plant hawk, a Lidl pub in Belfast, a junkyard playground, Flight 1073, endless sirloin, and a Monopoly board that cost 100% more to make here, plus the Kelce rebuild, the 81-81 Astros, Uber’s stalled safari, a legal “Stairway,” and the Oasis reunion doc. The money desk goes deeper this issue: the almost-premium card tier, patient portals, the $499 HSA body scan, Treasury’s 351 crackdown, the AI “laziness tax” on idle cash, a town that said no to $10,000 a household, the two-year note’s quiet math, six pros on 5% yields, and what sits behind an annuity.
Quarter-end, and the long end did the talking. The S&P 500 closed Wednesday at 7,651.54, down 0.25% on the day and 1.89% below the Aug. 13 record of 7,798.99. The Dow fell 443.87, or 0.86%, to 50,906.05. The Nasdaq finished at 26,861.06, a hair higher, well off its Sept. 22–23 records. For the third quarter the S&P rose 2% and the Nasdaq 2.5% while the Dow lost 2.7%. Four names did the lifting. The Journal’s 10-year closed at 5.292%, a 24-year high. Treasury.gov put it at 5.29%, the 2-year at 4.88%, the 3-month bill at 4.20%, and the 20-year at 5.68%, above the 30-year at 5.64%. WTI $90.42, Brent $103.53. Desk gold $4,186.70 (the paper’s contract $4,155.60). VIX 16.34, VVIX 89.48. The letter’s vol-of-vol test passed by 0.52 at the close and was failing live Thursday morning. The September falsifier is settled: the fall caution survived its own test. Next dates: jobs Oct. 2 · inflation and banks the week of Oct. 12 · Fed Oct. 27–28 · the vote Nov. 3. North Star adds still only at 7,175 / 6,863 / week of Nov. 3.
Signals point to a market that can still levitate on four stocks while the average name and the bond market tell a harder story. VIX 16.34, still in contango (9-day 14.20, 3-month 18.37). VVIX 89.48 sits at the letter’s line, a pass at the close and a fail live Thursday. SKEW 141.92, easing. Against it: the 10-year at a 24-year high, a 20-year above the 30-year, Brent–WTI still a tanker-premium spread, and a quarter whose S&P gain was a four-stock story. The September letter still passes only one of three conditions for new equity money. The falsifier is behind us. Jobs Friday is the next print that can move the front end. It does not make the long end cheap.
We pulled Polymarket at 8:16 a.m. PT Thursday, Oct. 1. October Fed decision: no change 66.5%, a 25 bp increase 31.5%, a 25 bp cut 0.45%. Sunday Sept. 27 the crowd had about 64.5% on a hike. That is the flip of the week. Balance of power after the midterms: Democrats taking both chambers 63.5%, split 28.5%, Republican sweep 7.5%.
Crowd odds are a price, not a forecast. New York sued Polymarket’s U.S. arm as an illegal gambling operation. The paper identifies Polymarket as a Dow Jones partner. We cite the number when the story connects; we do not treat it as research.
Three sittings, none of them a forecast. First, duration. A 24-year high on the 10-year is not a reason to go longer. Match cash to the date you need it. Bills and floating-rate paper remain the parking spot. Second, the child accounts. Treasury will auto-create Trump Accounts for tens of millions of kids. The $1,000 seed for 2025–2028 births still needs an election, and claiming the account is a separate step. Put it on the same list as the 529 form. Third, the year-end credits. Premium-card hotel perks expire. Count them against trips you were already taking, and book the portal that actually posts, before Dec. 31 becomes the booking desk.
You don’t wait for the first drop to find the umbrella. If a 10-year at 5.29% changes a refinance, a 529, or a lump-sum choice, bring the statement. If there is a child in the house, bring the Social Security number for the new account. The sitting is the plan, not a product.
Capital Wealth Daily · Vol. III · No. 178 · Thursday, October 1, 2026. Reported from the Monday, September 28 through Thursday, October 1, 2026 editions of The Wall Street Journal — including the Personal Journal, Arts in Review, Sports, the opinion pages, Streetwise and Heard on the Street. Each paper’s own market tables are the previous session’s close; the desk’s close of record for this edition is Wednesday, September 30 (Yahoo Finance quotes and Treasury.gov par yields). Thursday’s live session is not used. Prediction-market odds were pulled from Polymarket’s public data at 8:16 a.m. PT Thursday. The paper identifies Polymarket as a Dow Jones partner. New York has sued Polymarket’s U.S. arm; crowd odds are a price, not an endorsement. The weekend editorial’s odds and meter, where cited, are the desk’s opinions, stated so they can be tested.