 Capital Wealth Daily
The Oil Got Cheaper. Moving It Didn’t.
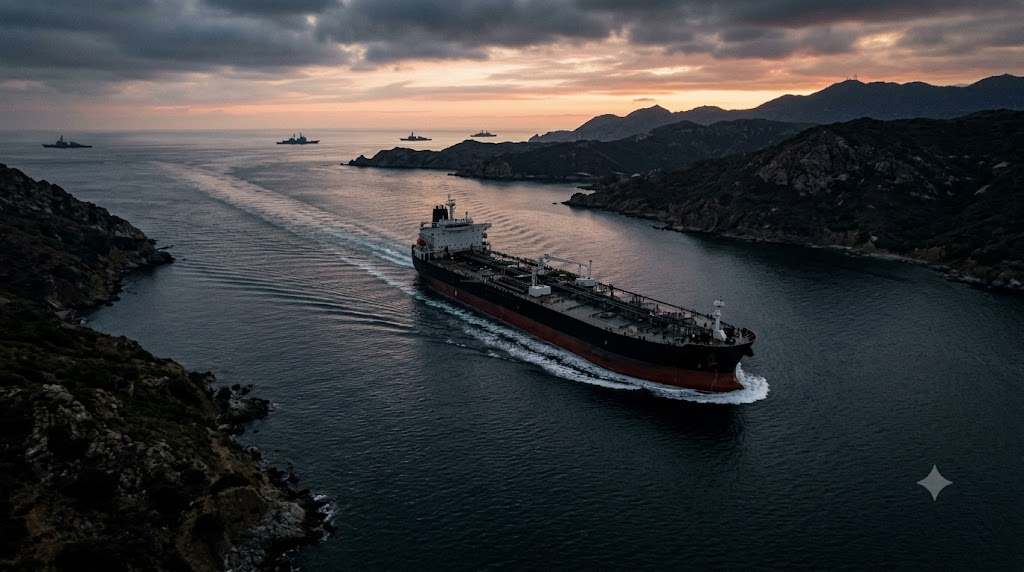
Crude fell four days straight. The ship that carries it costs $1 million a day.
October crude settled at $95.78 on Monday, down 4.5%. The Journal’s front page says drone strikes shut Saudi Arabia’s bypass pipeline and pushed supertanker rates to a record. That’s about $26 of freight on every barrel.
Our TakeA cheaper barrel isn’t a cheaper delivery. Budget for the freight, not the headline, and keep the energy hedge you already own at weight.
The Nasdaq closed at a record. It rose 2.26% to 27,122.09, its first record close since June. The S&P 500 gained 1.49% to 7,764.70, its best day since early August and 0.44% below the Aug. 13 record. Chips led. The semiconductor index rose 4.3%, AMD 10% and Intel 12%. Meta gained 11.4%.
Crude fell again. Shipping it didn’t. October WTI settled at $95.78, down 4.5%, its fourth straight decline. The Journal’s front page says hiring a supertanker out of the Persian Gulf topped $1 million a day earlier this month. That’s about $26 a barrel, roughly a quarter of the cargo’s value. Diesel hit $6.45.
The 10-year eased to 4.96%. That’s after a 19-year high above 5% last week. The Fed has raised its estimate of the neutral rate to 3.25%. The prediction market printed in the paper puts 62% on two increases this year. One is already done, so the crowd’s favorite is one more.
The life side of the paper. A retired United pilot with a $3.5 million 401(k) and a tax bill with a date on it, agents telling sellers to stop waiting for cheaper mortgages, a quarterback who was 99.9% sure to win, and the last night of John Waters’s summer camp.
Nothing new bought, for the fourth session. One of the September letter’s three conditions for new money is now met. Vol-of-vol (VVIX) closed at 85.77, under 90 since Thursday. Core inflation and the Fed still fail the other two. The nearest test that would prove the weekend editorial wrong, a record close above 7,798.99 before Oct. 2, is 0.44% away.
Off Duty · The Human File
7 stories · 3 pictured · 4 listed
John Waters closes his summer camp on his own terms, with 26 cartwheels and a Kool-Aid toast
The campers bought a community, and the host picked his own exit. Budget for the people, and put your last September on the calendar yourself.
Hold
The woman getting dumped on TikTok every week is happily married, and paid
Unlabeled testimonials are ads, and enforcement looks thin. Side-hustle cash is self-employment income, so pay the tax on it and open a Solo 401(k).
Hold
NC State had a 99.9% chance to win. Then its quarterback didn’t take a knee
Near the finish line, the job changes from scoring to not fumbling. A funded cash reserve is retirement’s take-a-knee play.
Hold- Off Duty · The Human FileTrump renamed Lake Ontario. The towns that voted for him three times are keeping the old nameHold
- Off Duty · The Human FileLane Kiffin left Ole Miss for LSU. The $6 million quarterback he left behind just beat himHold
- Sports · Trophy AssetsThe Lakers’ buyers see $30 billion in a decade, and the plan rests on one assumptionHold
- Personal Journal · Work & CareersMajoring in AI is like majoring in Excel. A Citadel veteran says study anthropology insteadHold
Your Money & The Economy
12 stories · 3 pictured · 9 listed
A retired United pilot has a $3.5 million 401(k), and the tax bill is the hard landing
A big pre-tax balance is a tax bill with a date on it. The cheapest years to shrink it are usually the ones between the last paycheck and the first RMD.
Hold
Five years near 7%, and the Fed went higher. Agents say stop waiting and price to the payment
Buyers shop the monthly payment, not the price. Run the buydown against the price cut before you answer an offer, and price the rent-it-out option too.
Hold
A $799 blood test for early cancer detection faces the FDA Wednesday. Medicare doesn’t cover it
New tests arrive years before insurance covers them. Put a funded line in the retirement budget for the ones Medicare won’t pay for.
Hold- Your Money · Claims & SettlementsTwo deadlines worth a calendar entry: Apple’s Siri settlement and the Twitter verdict payoutHold
- Your Money & The Economy · Family BudgetDisney cut prices, packed its parks and put a clock on every kid turning 10Hold
- Your Money & The Economy · Car BuyingJeep’s parent puts a floor under advertised car prices, and the real number gets harder to findHold
- Business · Franchise RiskThe burger that sank a 314-store Wendy’s operator, and a rancher’s fix for the price of beefHold
- The Economy · DieselDiesel hit $6.45 a gallon, and the refineries built to keep it cheap are in two war zonesHold
- Your Money & The Economy · Coastal RiskCitadel’s Miami tower stopped after a rig fell into traffic. The ground is the storyHold
- Work · The AI Build-Out‘The General’ walks 30,000 steps a day in a data center. Here’s what the AI build-out paysHold
- World · Work & CareersBurned-out young Chinese are starting one-person AI companies. Most clear under $1,000 a monthHold
- World · DeepfakesOne in eight election posts in Israel is AI-made. The same cheap fakes are aimed at your moneyHold
Markets & The Money
6 stories · 3 pictured · 3 listed
The 10-year went from under 1% to 5% in six years, and nobody can agree why
A 5% 10-year is income to lock if held to maturity. For long bonds, it’s a price risk. Keep the reserve short, and don’t build a plan that needs to know why yields rose.
Hold
Don’t count out corporate bonds. The Fed’s hikes may not repeat 2022
High-grade corporates may hold up. But spreads this tight mean you’re paid mostly for rates, not credit. Ladder maturities, keep quality high, close the cash gap.
Hold
Trump forms an AI Force, Huang agrees the fear is a hoax, and tech insiders sell $1 billion
Policy whiplash makes AI a concentration risk, and insiders are trimming winners. Hold at weight, and know how much of the plan is one theme.
Hold- Markets · CryptoA crypto bill died in the Senate, and the fight at its center was about what your cash earnsAvoid
- Markets · SpeculationPolymarket chased growth through a fraud wave, the Journal reports. It’s now raising at $21BWatch
- World · ChinaXi comes to Washington Thursday. The opinion pages say watch the words, not the dinnerHold
From the desk Bias, the book, what’s priced, the planopen
The Monday paper, and a market that went the other way from its front page. The Journal leads with a shortage nobody planned for. The short supply is in the ships that carry crude, not the crude itself. It warns that record freight could keep fuel expensive even if oil falls. Oil fell 4.5% on Monday. The lead, Crude Fell a Fourth Day. The Ship That Carries It Costs $1 Million a Day, explains why the pump may not follow. Then the 10-year’s six-year ride from under 1% to 5%, and what the bond market is and isn’t telling us. Heard on the Street on why high-grade corporates aren’t 2022. The AI Force and Jensen Huang against the doomers. A crypto bill that died, and the Journal’s Polymarket investigation. And Xi’s visit this week. The life side leads with the whole Personal Journal: a retired pilot’s tax torpedo, selling a house at 7%, the case for anthropology, and John Waters’s final camp. Plus a quarterback who was 99.9% sure to win, the TikTok breakups that were ads, and a renamed lake whose own voters won’t use the new name.
Stocks went the other way from the weekend’s worry. The S&P 500 rose 114.20 points, or 1.49%, to 7,764.70. That was its best day since early August and 0.44% below the Aug. 13 record of 7,798.99. The Nasdaq Composite gained 599.55 to 27,122.09, a record close and its first since June. The Dow added 366.19 to 52,048.83. Leadership was loud and narrow. The PHLX Semiconductor index rose 4.29%. Advanced Micro Devices rose 9.95% to $615.52, a market value of about $1 trillion. Intel rose 12.14%. Meta Platforms rose 11.43% after, per market reports, Wells Fargo raised its price target and its Muse assistant reached No. 1 on Apple’s U.S. App Store. The equal-weight S&P ETF rose 0.56% and the Russell 2000 0.52%. Crude fell a fourth day. October WTI settled at $95.78, down 4.5%, and Brent at $100.34, as Hormuz traffic was reported at a six-month high. Energy stocks followed it down (Exxon −3.2%, Valero −4.8%). The 10-year eased to 4.96% and the 2-year held at 4.76% (Treasury.gov). The VIX closed at 14.87 and vol-of-vol at 85.77. It wasn’t a broad rally, but it was a calm one.
Signals point to a calm market with narrow leadership and a front end still priced for more. The volatility index closed at 14.87 with its curve in contango, meaning later dates priced higher. The nine-day gauge was 13.14 and the three-month 18.08. Vol-of-vol (VVIX) sat at 85.77, under 90 for a third session. The SKEW index eased to 142.19 from 148.10. By SKEW, that’s the calmest close of the month. By vol-of-vol, it’s the calmest since Sept. 4. Against it: the S&P 500 is 0.44% below its record on a day the equal-weight index rose well under half as much. The 2-year sits at 4.76%. The paper’s prediction market puts 62% on two increases this year. And freight and diesel are writing an inflation story crude isn’t. The September letter’s conditions for new money now pass one of three, vol-of-vol under 90. They still fail the other two. Core inflation ran 0.3% against a 0.1% test, and the Fed raised. The weekend editorial wrote down what would prove it wrong. The nearest is a record close above 7,798.99 before Oct. 2. If it prints, we said we’d be wrong, and we’ll say so. None of this is a forecast.
The Journal printed a new prediction market this week. Polymarket’s How many Fed rate hikes in 2026? puts 62% on two, 19% on one, 18% on three and 2% on four. That’s as of 2:30 p.m. ET Friday, on $525,433 wagered. The Fed has made one already, so the crowd’s favorite is one more this year. The Fed’s own projections raised the long-run neutral rate to 3.25% from 3.1%.
Our own pull of Polymarket’s most-traded markets, at 10:46 p.m. PT Monday. October Fed decision: 52.5% on a quarter-point increase, 46.5% on no change. Xi visits the U.S. by Sept. 24: 99.7%. September WTI: 64.5% that crude touches $90 or lower before the month ends, 34% that it sees $100 again. Balance of power after the midterms: 64.5% on Democrats taking both chambers, 29.5% on Republicans holding the Senate while Democrats take the House.
The borrowing table: prime 7.00%, SOFR 3.85%, the 30-year mortgage 7.05% on Bankrate’s survey and 6.95% on Freddie Mac’s. A 48-month car loan is 7.04%, against 4.25% to 4.69% at the best credit unions. The average money-market account pays 0.44%.
Source note. The paper identifies Polymarket as a Dow Jones partner. Today’s front page carries the Journal’s investigation of its compliance record. We carry crowd odds as crowd odds, each with its own timestamp. They are a price, not an endorsement of the platform.
Market-implied expectations, not forecasts. They move intraday and have been wrong before. Not investment advice.
Three things worth fifteen minutes this week, and none needs a forecast. First, the fuel line in the budget. Crude fell 4.5% on Monday. Freight and diesel may not follow it down. If you drive, heat with oil or buy groceries, budget for the delivery, not the barrel. Second, the distribution you haven’t met yet. The retired pilot in today’s Personal Journal has a $3.5 million 401(k). His income jumps past $300,000 when required distributions start. If your pre-tax balance is large, the years between the last paycheck and the first RMD are usually the cheapest window to shrink it. Medicare’s surcharges belong in the math. Third, the cash. Bills auctioned near 4%. The average money-market account pays 0.44%. A 3.75% stablecoin reward isn’t a deposit. Know which one your cash is sitting in.
Bring the statement and we’ll go line by line. We’ll cover the pre-tax balance and your RMD year, where the cash sits, and what you’d do if the market gave back 8% in October.
Book 15 minutes — phone or Zoom →Capital Wealth Daily · Vol. III · No. 175 · Monday, September 21, 2026. Reported from the Monday, September 21, 2026 edition of The Wall Street Journal — including the Personal Journal, Arts in Review, Sports, the opinion pages, Streetwise and Heard on the Street — whose own market figures are the Friday, September 18 close. Monday’s closing levels are from Yahoo Finance quotes and Treasury.gov daily yields; the drivers of Monday’s session are as reported by financial news services. Prediction-market odds: the market printed in the newspaper carries its own timestamp; the others were pulled from Polymarket’s public data at 10:46 p.m. PT Monday. The paper identifies Polymarket as a Dow Jones partner. The weekend editorial’s odds and meter are the desk’s opinions, stated so they can be graded, and are not forecasts. Written and edited by the Capital Wealth LG research desk.