 Capital Wealth Daily
Inflation Stayed Sturdy, the Fed Moved Closer to a Hike, and Brunch Is Over.
August’s Core Inflation Ran Hot and Pulled the Fed Toward a Hike. The Fight Now Is Whether One Is Enough.
Headline inflation held at 3.4% over the year. But core prices rose 0.3% in August, faster than forecasters expected. Interest-rate futures moved the odds of a quarter-point hike next week to about 85%, from 70%. Inside the Fed, the harder argument is about what comes after.
Our TakeNobody knows yet whether one increase becomes three, so plan for both. Keep cash where a hike helps. Budget any borrowing without counting on cuts. Action: nothing new bought. The September letter’s conditions went unmet, and the safe money stays short.
The week finished down even after Friday’s bounce. The S&P 500 fell 0.80% to 7,656.98, the Dow 1.57% and small companies 2.41%. Friday itself rose 0.86% on a hot inflation report.
Bonds and oil kept their week. The 10-year Treasury finished Friday at 4.975%, its highest since 2023, and crude rose about 9% on the week to roughly $100 a barrel.
Inflation-proofing made the money pages. Jason Zweig’s Intelligent Investor makes the case for a ladder of Treasury inflation-protected securities. Real yields on some recently topped 3%.
Off Duty declared brunch over and road-tested a 1,139-horsepower electric Porsche Cayenne. It starts at $163,000 and came to $198,180 as tested.
Nothing new was bought. Friday’s core print ran a tenth hot, and a rate increase became the market’s base case for the Sept. 15–16 meeting. So the September letter’s conditions for new money weren’t met.
Off Duty · The Human File
11 stories · 3 pictured · 8 listed
Brunch Had a Good Century. Now It’s Lunch’s Turn.
A set-price lunch shows most of the bill up front. Give dining out its own budget line, and a pleasant habit won’t turn pricey.
Hold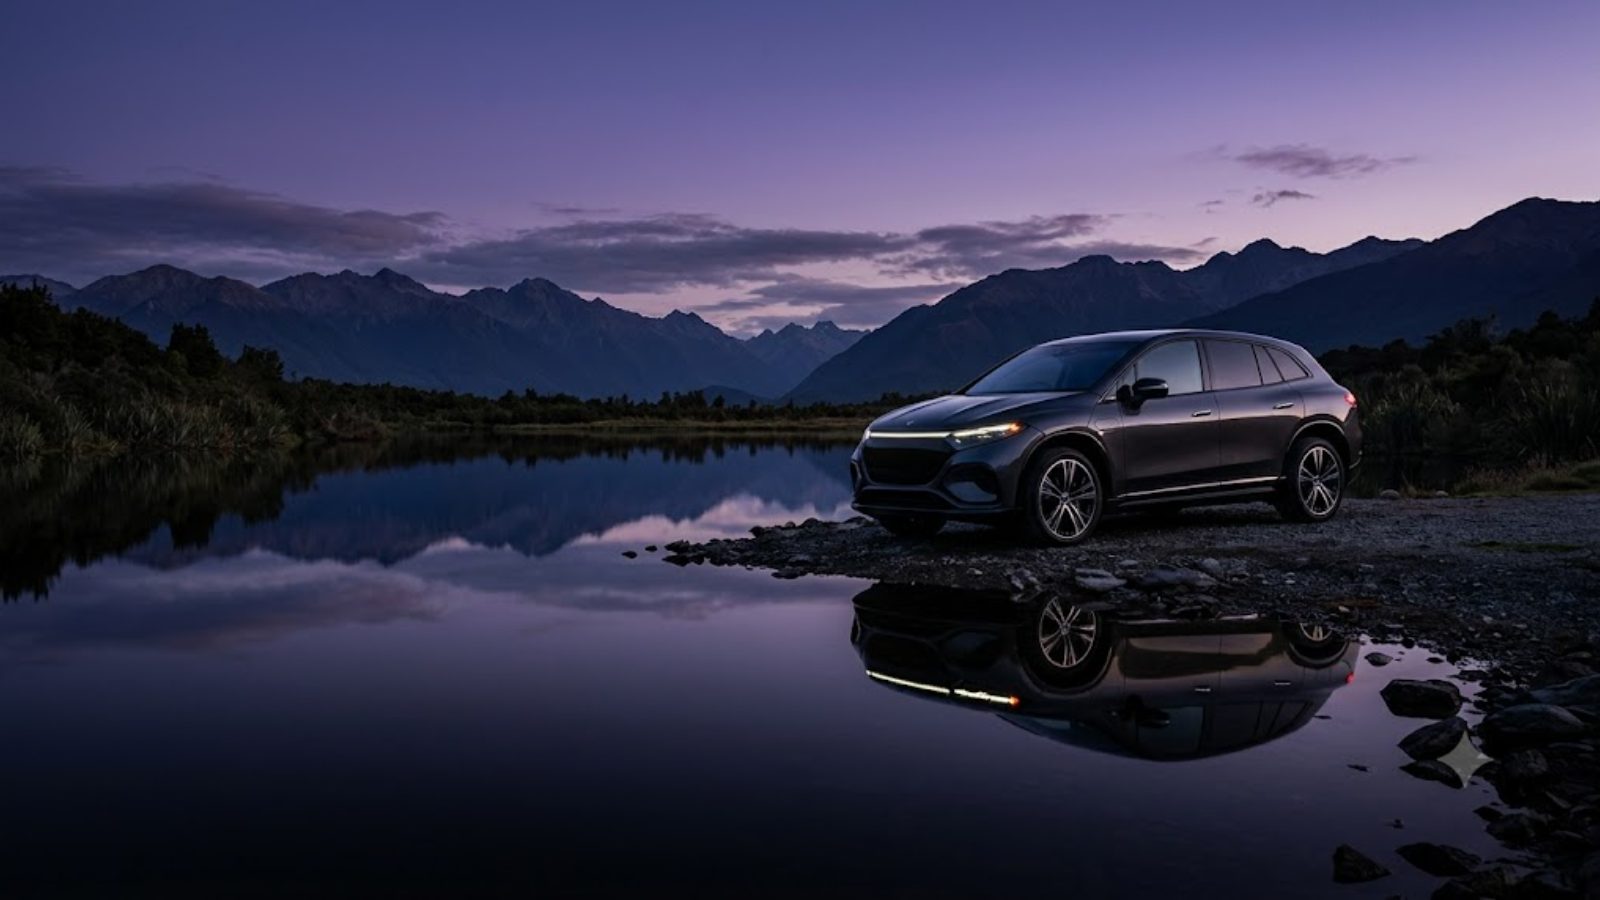
A 1,139-hp Porsche SUV, and Why the Cheaper Trim Wins
A car is the most enjoyable thing most people buy that loses value. Set the all-in price first, and pay from money already set aside for it.
Hold
Seven trees on one mirror: the rideshare scent war
Side hustles live on small details. Track the little costs. The customer decides what’s too much and whether to ride again.
Hold- Sports · College FootballCollege kickers compared paychecks. Then they got raises.Hold
- Off Duty · TravelTaipei’s Temples Are Nearly All Free. The Trip Isn’t.Hold
- Off Duty · CultureSix Fall Movies Worth Leaving the Couch ForHold
- Off Duty · StyleWearing 3,000-Year-Old Gold Comes With Hard QuestionsHold
- Off Duty · DesignStainless Is the New Sterling. Buy It for the Long Haul.Hold
- Off Duty · Eating & DrinkingCrispy Zucchini Fries for Hosts Who Fear the FryerHold
- Review · FamilyOreo-Gate Hit a Nerve. Ask Who Profits From the DramaWatch
- Review · The ObituaryNew Coke Flopped. Coke, and Brian Dyson, Came BackHold
Your Money & The Economy
7 stories · 3 pictured · 4 listed
Inflation Overstayed. Zweig’s Answer Is a TIPS Ladder
Give every safe dollar a due date. Treasury bills cover near-term needs. Add longer inflation protection only after weighing duration and taxes.
Hold
Ask Early, Don’t Bluff, Don’t Quit: New Rules at Work
For many people in their 50s and 60s, earning power is the biggest asset. An emergency fund is the insurance that buys time if work wobbles.
Hold
The Talk Was Work. The Hosts Thought It Was Free
If you consult or speak in semi-retirement, settle the fee before the work. Price your time like the asset it is.
Hold- Review · The American DreamReaders on the American Dream: Own Slowly, Skip the BoatHold
- Exchange · MarketsA Hot New Name Can Cost You. Read Past the LabelWatch
- Exchange · Tech ReviewThe $1,999 Folding iPhone: Tempting, Heavy, PriceyHold
- U.S. News · GoldAccused of taking $40M in gold, a CIA officer nears a dealHold
Markets & The Fed
6 stories · 3 pictured · 3 listed
The AI freakout went mainstream. Experts aren’t sold.
Here’s the planning version of AI anxiety. Gauge how much of your paycheck the technology could touch, and don’t let a scary week pick your investments.
Hold
Anthropic’s possible record IPO: a case for patience
A record-size listing is a reason to wait for the public filing, and to know what your index funds own before adding a single new stock.
Watch
AI’s math breakthrough: separate promise from price
A breakthrough and a stock price are separate questions. Judge the business and what you’re paying before adding to any AI theme.
HoldFrom the desk Bias, the book, what’s priced, the planopen
The Weekend paper arrived with Friday’s inflation report still warm. Core prices ran hot, futures moved to roughly 85% odds of a hike, and the argument inside the Fed turned to whether one would be enough. The week read two ways. Stocks got their Friday back, while bonds and oil kept their week. Exchange had the useful answer to inflation that won’t leave, Jason Zweig’s TIPS ladder. It also had Anthropic’s possible record IPO and Kalshi’s round-the-clock stock bets. Off Duty called time on brunch and put a 1,139-horsepower Porsche on the road. And the front section found America’s AI anxiety, a CIA officer accused of taking gold, a fight over what a rideshare should smell like, and college kickers finally getting paid.
The Weekend paper’s figures are Friday’s close, and the week reads two ways. Friday was a relief day. The S&P 500 rose 0.86% on a hot core inflation print, because the annual rate eased and crude slipped back under $100. The volatility index fell 11% to 15.84. The week wasn’t a relief. The S&P 500 finished down 0.80%, the Dow 1.57% and the Russell 2000 2.41%. The 10-year climbed to 4.975% and crude gained about 9%. Stocks got their Friday back. Bonds and oil kept their week, and that’s the setup the Fed walks into.
The signals point to caution in long bonds more than in stocks. The volatility index fell 11% on Friday to 15.84, and the curve of volatility futures steepened back into a calm upward slope. But the skew measure rose. That’s what traders pay for protection against a sudden drop. So the market is calm day to day and still paying up for a gap. Vol-of-vol finished at 91.3, just above the 90 line the September letter drew. With core inflation hot and a rate increase now the base case, the letter’s conditions for new money aren’t met. The answer for now is to wait. None of this is a forecast. It’s how the portfolios are positioned with two big events on next week’s calendar, the Fed’s decision Wednesday and Friday’s quarterly options expiration.
We pulled these Friday afternoon, after the inflation report. Prediction markets put about 80% odds on a rate increase at the Sept. 15–16 meeting, up from roughly 60% before the release. They put 94% odds on no rate cuts at all in 2026.
The longer-dated contracts were calmer than the headlines. A recession by the end of 2026 sat near 7%. The S&P 500 touching 7,400 at some point before year-end sat around 72%. On oil, the crowd gave roughly 34% odds to West Texas crude touching $110 this month. Strait of Hormuz traffic returning to normal by Dec. 31 got only 20%.
Read these as the crowd’s expectation at the moment we pulled them, and nothing more. They move during the day, and they’ve been wrong before. Fed Week’s edition, No. 170, carries Tuesday’s odds.
Crowd odds, not forecasts. Not investment advice.
Three things are worth fifteen minutes this weekend. First, where your idle cash sits. The gap between a bank money-market rate and a Treasury bill is still the widest easy money in the paper. Second, whether the spending you can put a date on is matched to money that comes due in that year. Think of the years before Social Security starts, a tuition bill or a planned purchase. That’s the idea behind the TIPS ladder in this weekend’s Intelligent Investor. Third, the fun money. The car, the trip, the ring. What it costs to own, insure and replace, not just what it costs to buy.
Bring the statement and we’ll go line by line. Where the cash sits, how long the bonds are, and what next week’s Fed meeting would actually change for you.
Book 15 minutes — phone or Zoom →Capital Wealth Daily · Vol. III · No. 169 · Saturday/Sunday, September 12–13, 2026. Reported from the September 12–13, 2026 Weekend edition of The Wall Street Journal — the A section, Exchange, Review and Off Duty — and from the Capital Wealth Growth Portfolio review notes. Figures are the Friday, September 11 close. Prediction-market odds were pulled Friday afternoon, Pacific, after the inflation report. Written and edited by the Capital Wealth LG research desk.