 Capital Wealth Daily
Life, Books, and the Price of Everything
Part II of the mid-week review. Our read of the July 11–14 Wall Street Journal (Monday, July 13 close), and what the model books did about it.
Texas built a stock exchange. On opening day, almost nobody came.
It started at a Houston dinner in the fall of 2022. Greg Abbott told a half-dozen friends the Lone Star State should have its own stock exchange. Across the table sat James Lee, the man who’d go on to build it. On Friday at 9:30 a.m., the Texas Stock Exchange (TXSE, “tex-ee”) opened for real. First came practice runs, in which Goldman Sachs (GS) and Citadel Securities traded mock symbols. It opened from temporary offices in Dallas with a handful of small stock symbols. The timing is no accident. Stock trading has never been bigger. SpaceX’s $86 billion IPO was the largest ever. OpenAI and Anthropic could go public within months. And Texas would very much like to grab land from the NYSE–Nasdaq duopoly. It took Nasdaq two decades to get competitive with the NYSE. TXSE is on day three.
Our ReadNo action, and that is the action. An exchange is a network business. A network with a handful of tenants is a building, not a moat. TXSE goes on the watch list with one specific tripwire. We care when a real listing moves, not when a ribbon gets cut. Goldman (GS) stays reinforced. It makes money on the plumbing no matter whose orders run through it. That is exactly why it survived the last three “NYSE killers.” For clients the read is simpler. Where your shares trade has never once decided whether your plan works. Fees, taxes, and time do that.
The Stories
6 stories · 3 pictured · 3 listed
Gold was supposed to catch you. Gold is down 25%.
This one costs us something, and we say so. The metals sleeve (WPM, RGLD, IAU) is our worst-performing position of the year. A 25% drop from January is a real hole in a real book. We are not adding to it, and we are not dumping it. A hedge you sell at the bottom was never a hedge. It was a trade in a costume. What we are doing is being honest about the job it failed at. Gold did not catch the stock drop, and neither did bonds. That’s the whole Risk Atlas argument. SGOV stays reinforced at 4%+ because bills are the one cushion that has never argued with us.
Shein got Beijing’s blessing. The price tag came back a third smaller.
Avoided, and not a close call. This company has been marked down from $66 billion to maybe $40 billion, across three failed listing venues in three years. That is not a growth story. It’s a way out for the people who got in at $66 billion. We don’t buy other people’s exits with retirement money. The bigger tell matters more than the ticker. The IPO window is open (SpaceX at $86B, OpenAI and Anthropic circling), and that is exactly when the merchandise gets mixed. Our IPO rule holds. We buy the second annual report, not the first roadshow.
Oil jumped 9.42% in a day. The insurance sleeve did its job.
Chevron (CVX), Exxon (XOM) and ConocoPhillips (COP) stay reinforced. This is the fourth straight edition we’ve said the thin buffer was the reason to hold them. Monday is what that looks like when it pays. The pipes (KMI, WMB) keep collecting tolls, and TPL keeps collecting royalties on other people’s urgency. Note what a 9.42% day actually tells you. The SPR is not a price cap, it’s a delay. We are not adding into the spike. The sleeve was sized for this in advance, which is the only time sizing is worth anything.
Off Duty & The Life File
6 stories · 3 pictured · 3 listed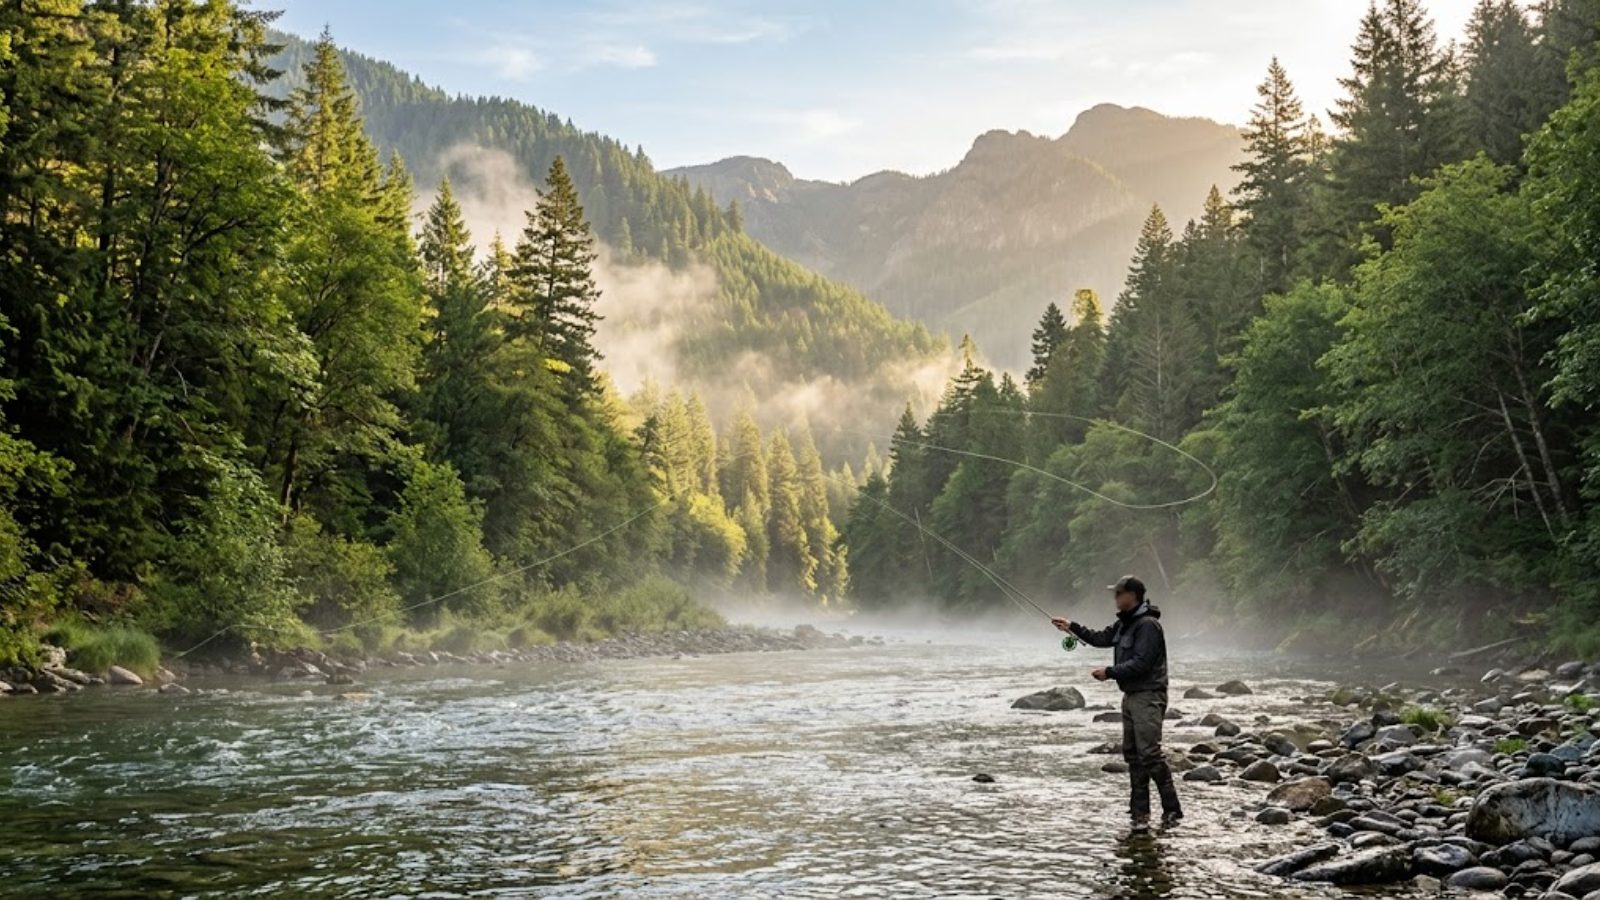
Learning to fly, badly, in the Catskills.
On the Beaverkill, where American dry fly fishing was born, our man tangles his line in the same hemlock three times before breakfast. Loading move. Power snap. Cannonball. The cradle of a pastime is also its best classroom. Every expensive skill starts with a bad Tuesday.
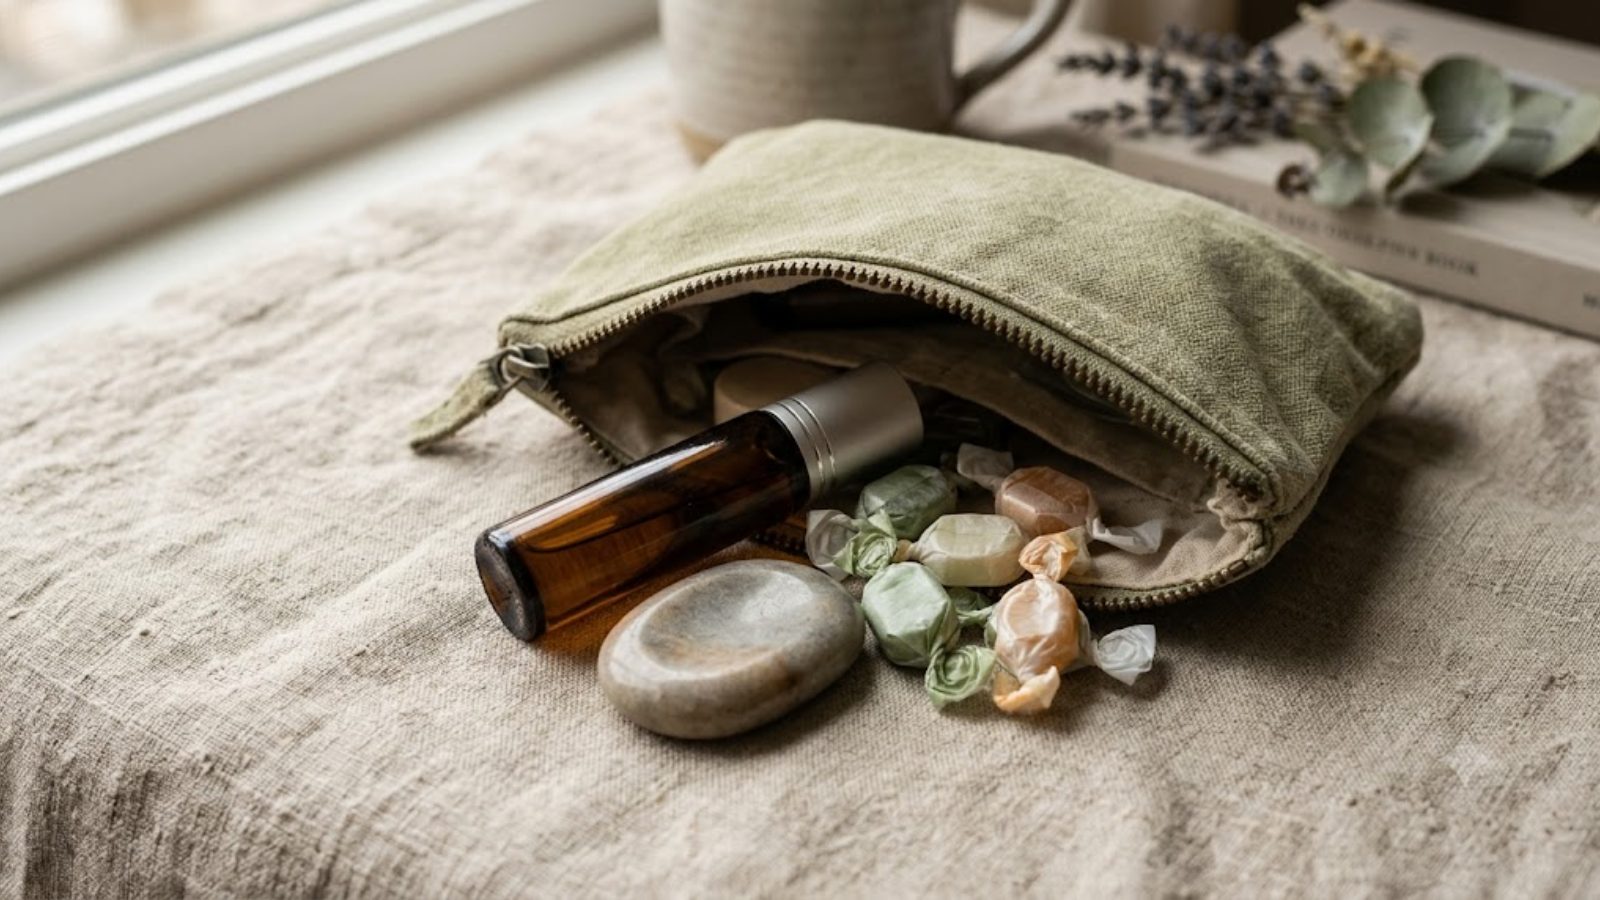
The “panic pouch” is now an accessory.
Fidget toys, prayer beads, lavender oil, a portable fan, sour candies. Carried daily, used a few times a week. Behavioral risk is Risk 08 on our own map. An entire consumer category has quietly grown up around it. The market has priced your nerves before you have.
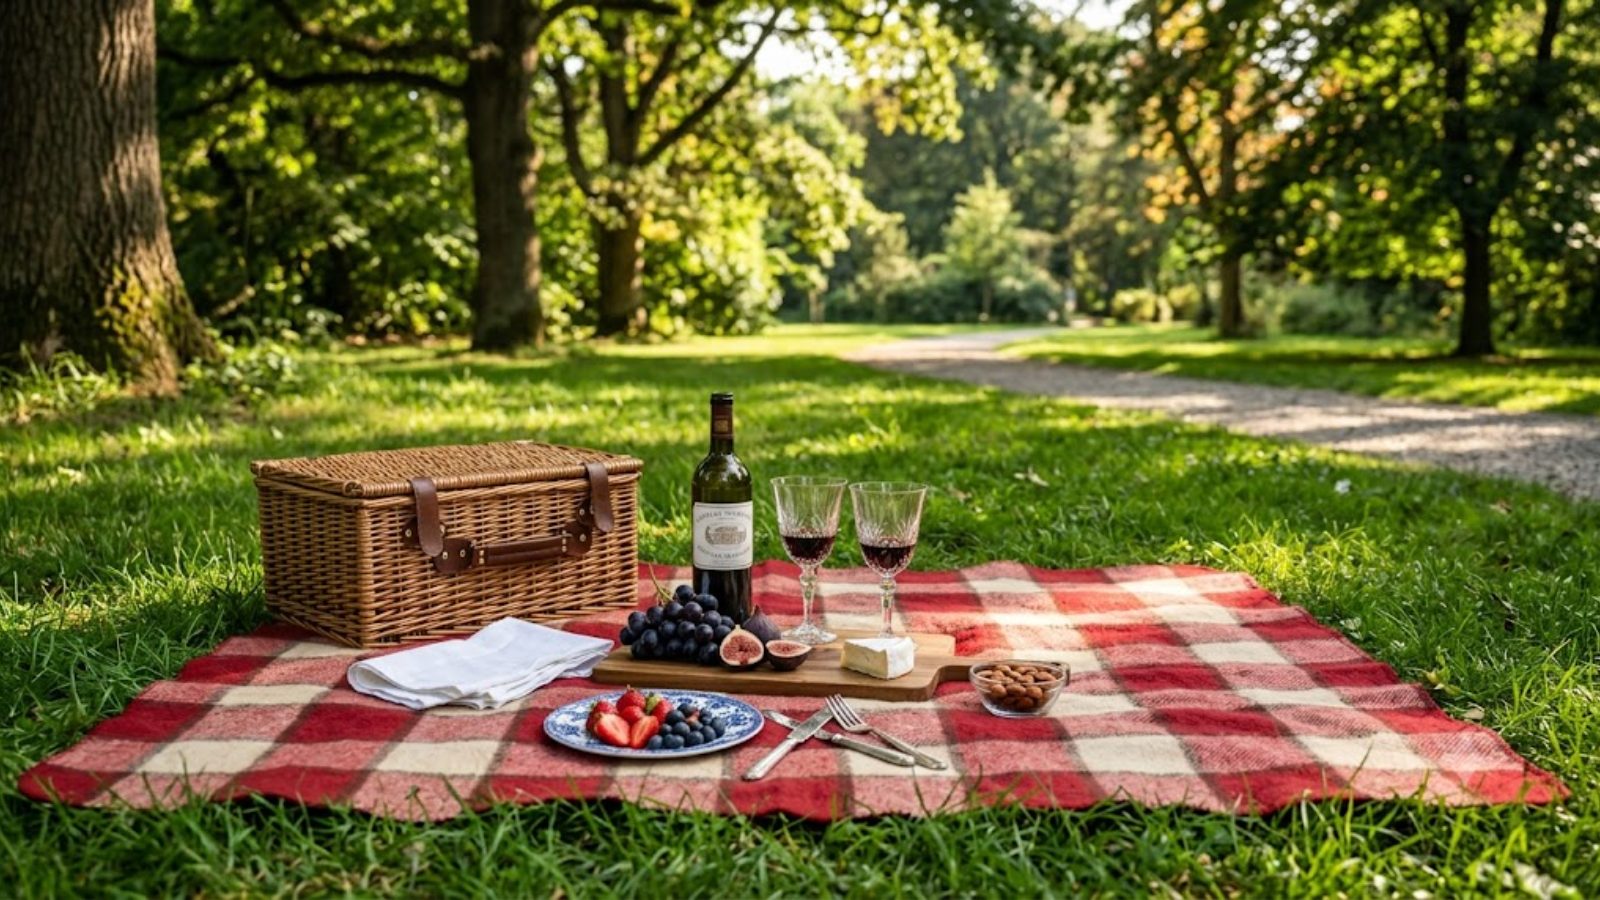
Everything else is in decline. Bubbles are up.
The global sparkling wine market hit nearly $50 billion in 2025 while other drink categories slid. The most durable consumer businesses sell the small affordable luxuries people protect when they cut everything else. That is the same reason DG sits in the value books.
From the desk Bias, the book, what’s priced, the planopen
Down, narrow, and, for once, with no cushion. Monday was the tell. Nasdaq −1.55%, S&P −0.79%, Dow −0.26%, and gold fell 2.6% right alongside them, now 25% under its January record, while the 10-year sat at 4.610%. Stocks down, gold down, bonds not catching. That’s the diversification promise failing in all three lanes on the same afternoon. Oil is the exception, and it’s a geopolitical one: +9.42% on Pentagon strikes, not on demand. We are leaning into the sleeves that pay us to wait (energy, dividends, bills). We are refusing every story that needs a stranger’s exit to work.
- DJIA52,498.64 −0.26%
- S&P500 7,515.34 −0.79%
- NASDAQ25,873.18 −1.55%
- STOXX600 641.01 −0.01%
- 10Y 4.610% 2Y4.261%
- OIL$78.14 +$6.73 (+9.42%)
- Gold $3,997.00 −$107.10 (−25% from Jan record)
- EUR$1.1383
- JPY162.46
Gold fell 2.6% on a down day for stocks. Not falling was its one job. If your plan assumed a cushion, this is the week to find out whether you own one or just believed in one.