 Capital Wealth Daily
Social Security Has a Date. So Does the Eclipse, the Wedding and the Trip After the Diagnosis.
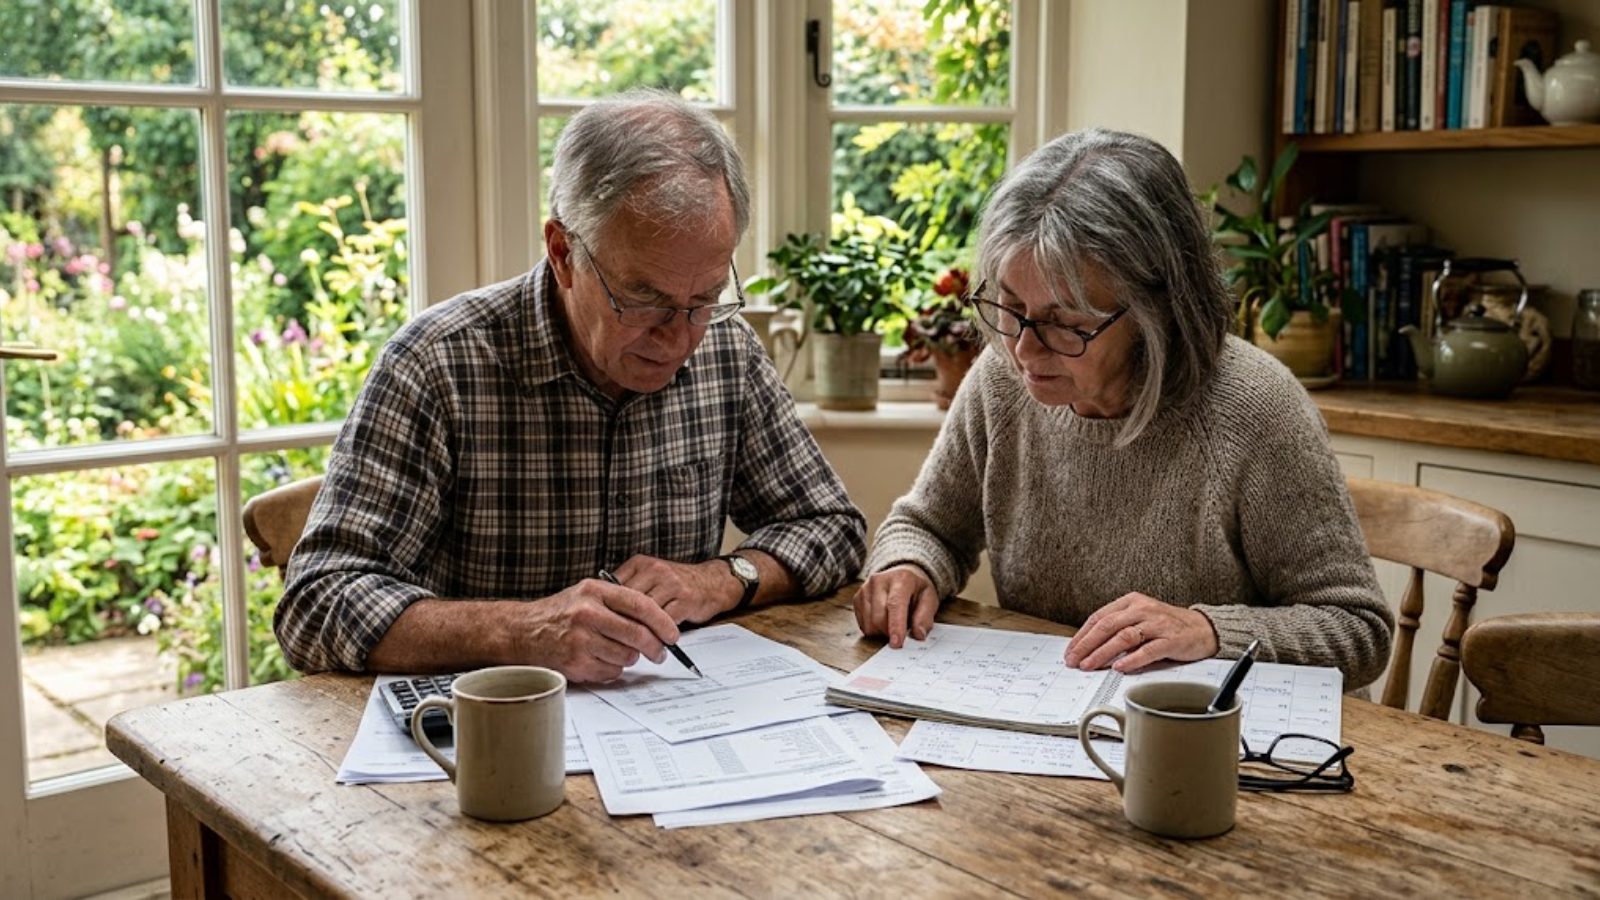
Congress Says It Is “Not Sleepwalking” Toward 2032. It Is Walking Very Slowly.
The retirement trust fund runs dry in six years. Then benefits get cut 22% automatically. Senators are floating boards, commissions and lifting the payroll cap. None of it is a bill yet, and the two leading Republican sponsors are retiring. So the most predictable problem in American finance now has senators talking about it. That is progress. It still has no bill. That is the point.
Our TakeNothing in the book changes on a bill that does not exist. In every retirement plan we run, we cut the Social Security line 22% from 2032. It stays cut until Congress gives us a reason to put it back. Action: A patch is the base case. A cut is the stress case. A plan that survives the stress case survives the patch for free. That is why we model the smaller number.
Congress is finally talking about Social Security’s 22% automatic cut in 2032. Nobody has filed a bill. For now, the working assumption is 78 cents on the dollar after that year.
A 92-year-old retired teacher lost $694,000 to a niece she had cut out of her will. A court voided the new will. A power of attorney, a successor trustee who is not the caregiver, and a trusted contact would have stopped it.
About 7.4 million Americans over 65 live with Alzheimer’s dementia, and more of them want to keep traveling. The doctors say go early, go familiar, go direct.
The average wedding costs $34,200, and 31% of couples borrow or ask family. Brides with 3,000 followers now get $600 a post from sponsors.
Muskoka rentals for next summer are up 110% thanks to three television shows. Eclipse chasers are booking Aug. 2, 2027, at $7,300 for the Nile and $27,000 for Gibraltar.
Off Duty · The Human File
11 stories · 3 pictured · 8 listed
The trip is the medicine. Even after the diagnosis. Especially then.
Travel is a fixed cost you spend early, in the healthy years. It is not what’s left over. Give it a dated line in the plan, funded from income and bills.
Add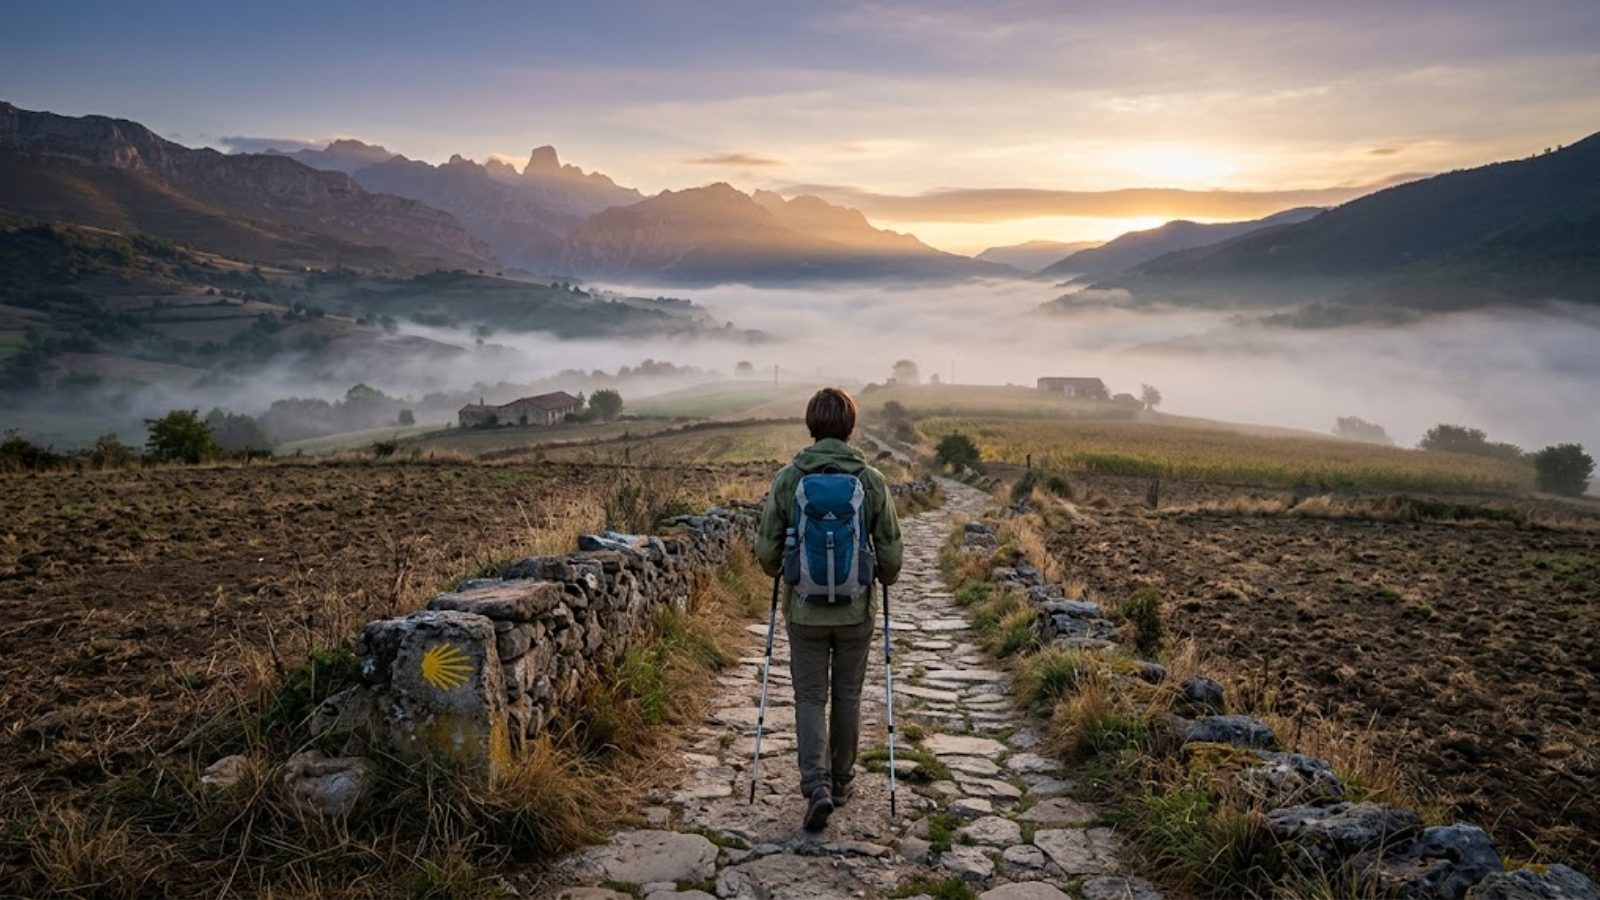
She lost her job to the AI cuts and walked 500 miles across Spain to find the next one.
She could walk because the runway existed. Past fifty, the emergency fund is a job-search fund. A year in bills, sized before the letter comes.
Hold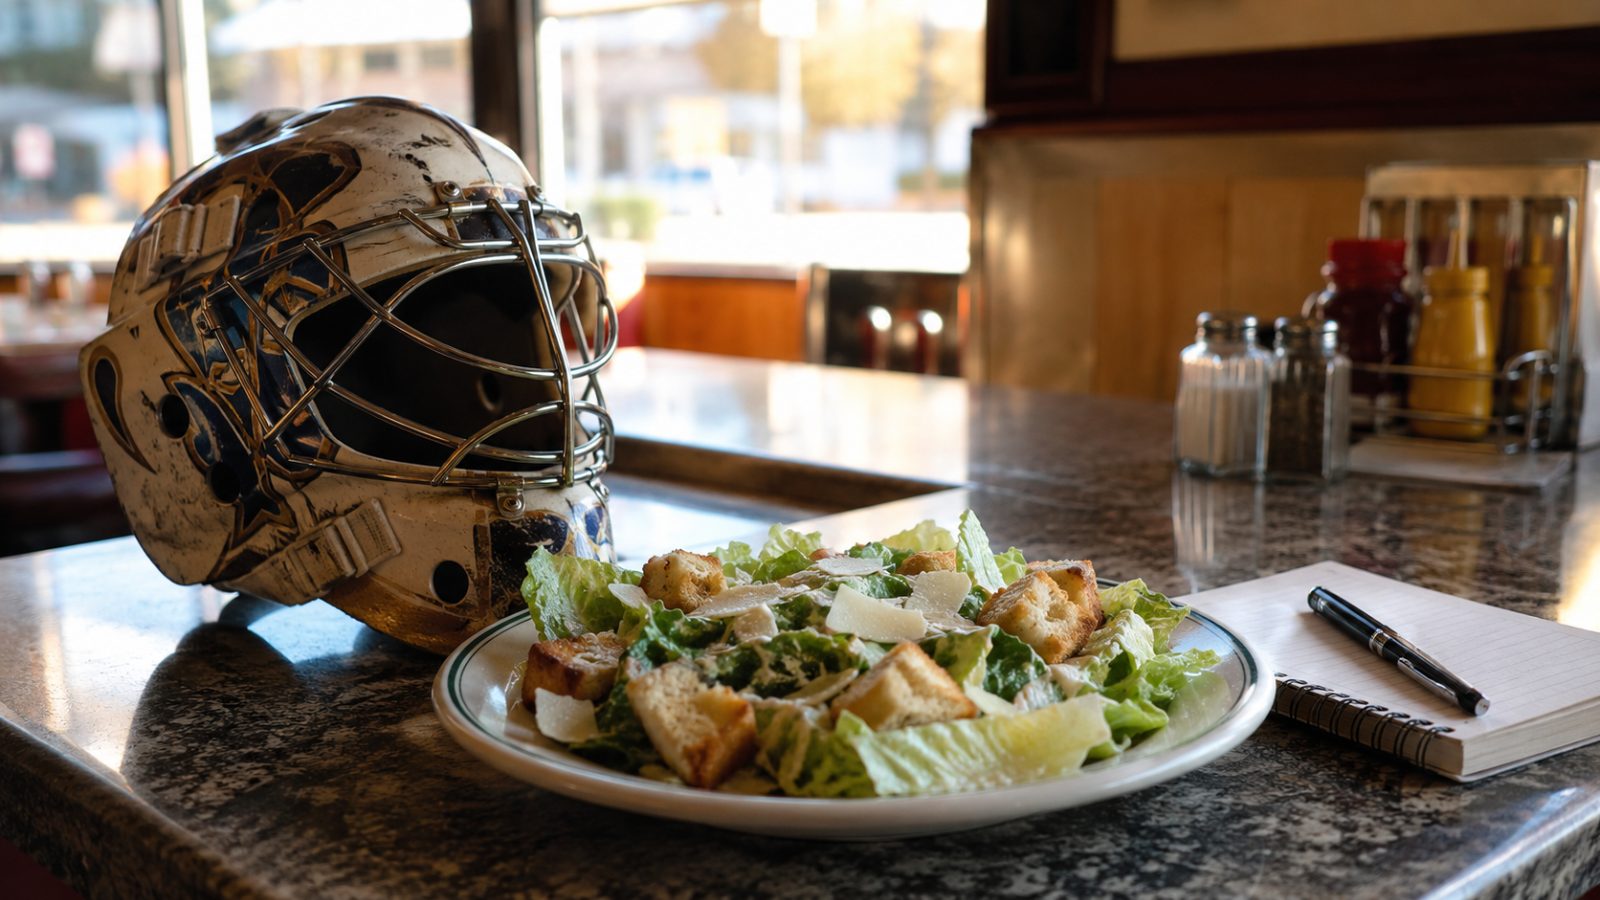
Team USA’s gold-medal goalie has a side hustle: she rates Caesar salads. Milan got a 5.4.
The best second act starts while the first one is still paying. The best side gig is one where failing only costs you lunch.
Hold- Off Duty · Reader Mail“Back in the ’70s in our 70s.” The readers have opinions about seniors and weed.Hold
- Personal Journal · TravelTen new ways to Europe for summer 2027, a $50 Amtrak lounge and the Night Owl fare.Hold
- Off Duty · TravelRope swings off a cliff, highlines across a canyon, tandem BASE jumps. The guides take clients from 10 to 69.Hold
- Your Money · Travel With a DateThe eclipse chasers are already booking August 2, 2027. The Nile cruise is $7,300 and the Gibraltar ship is $27,000.Hold
- Off Duty · TravelGenoa was the world’s banker in 1620. Now it is the one big Italian city without a crowd.Hold
- Off Duty · TravelThe Aztec capital is still under Mexico City. You can reach it by barge, sweat lodge and hotel lobby.Hold
- Off Duty · StyleThe bottle tan grew up. Mists, drops and undertones, and nobody should be able to tell.Hold
- Off Duty · ReviewBehold the hairless he-men of summer: buff, burly, smooth as a Ken doll, and worth tens of billions to someone.Hold
Your Money & Your Years
6 stories · 3 pictured · 3 listed
A retired teacher, 92, had $694,000 taken by the niece she had disinherited.
“If you’ve got your squad, it’s a lot harder.” That squad is a power of attorney, a successor trustee who is not the caregiver, a trusted contact at every bank, and someone reading the mail.
Hold
Two fortunes, two family wars, one missing piece of paper.
The math scales down. The fights do not. Get a prenup or postnup, and an incapacity plan with an agreed trigger. Sign them on a calm afternoon.
Hold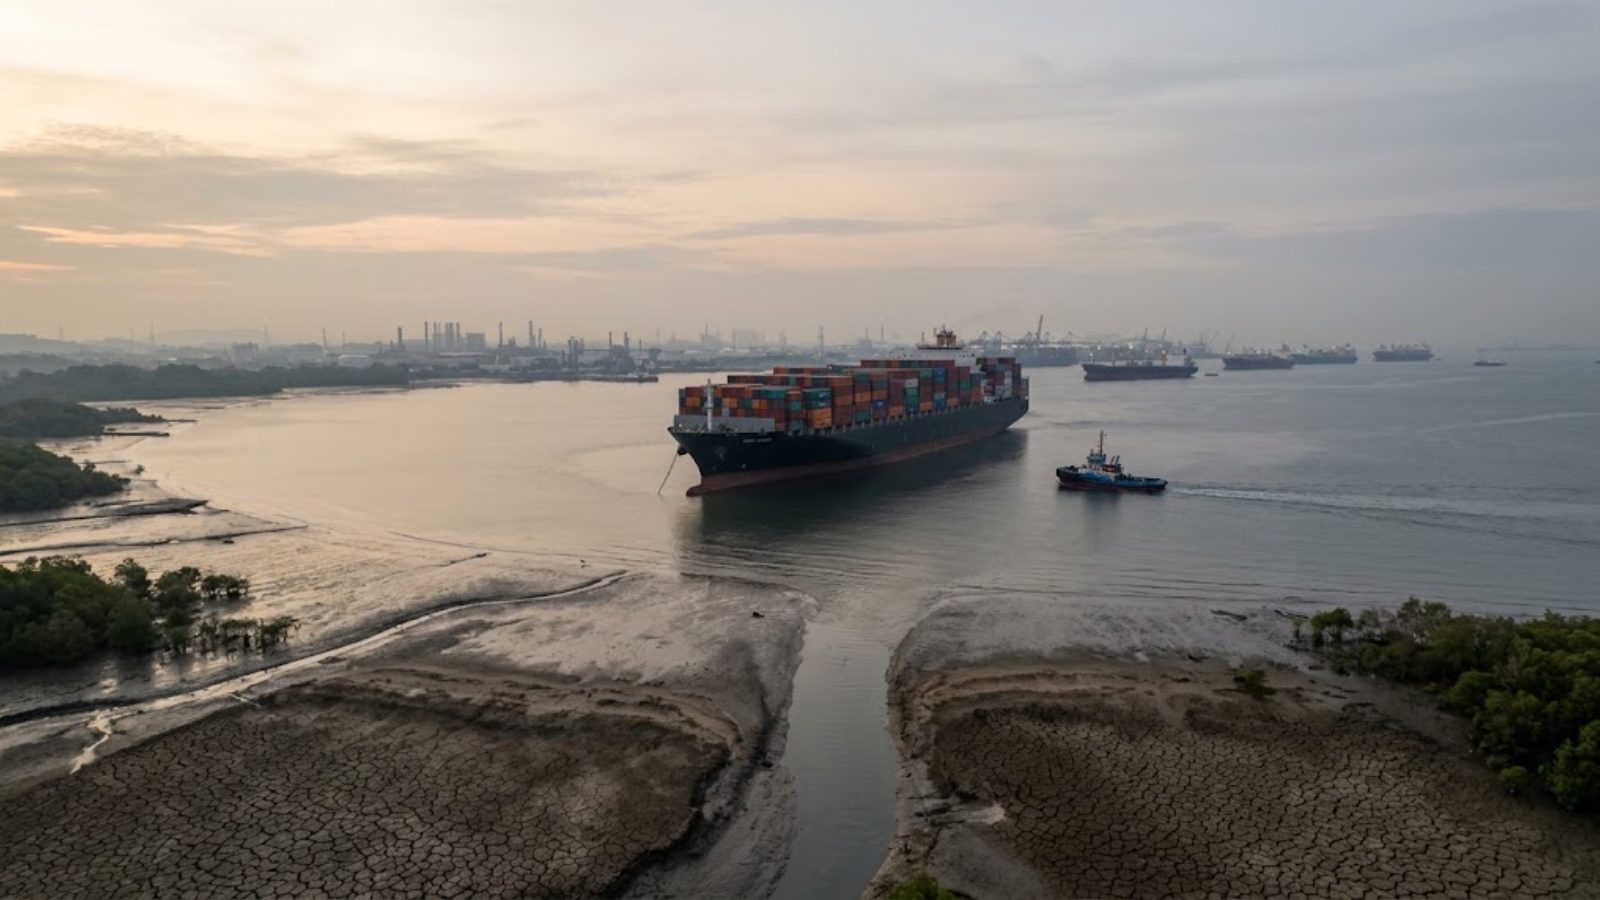
El Niño is coming for the Panama Canal, the copper mine and your grocery bill.
Weather is the inflation nobody can hike against. The inflation-linked sleeve stays a permanent line. It is not a trade.
Hold- Journal Report · Travel & AgingDementia doesn’t have to be the end of travel. The doctors say go early, go familiar, go direct.Hold
- Style & Fashion · WeddingsBrides make bank. The $34,200 wedding now comes with sponsors, and 31% of couples are still borrowing.Hold
- Your Money · Second HomesCanada’s “Hamptons” is on three TV shows at once. Next-summer bookings are up 110% and the Ritz starts at $6.5 million.Watch
From the desk Bias, the book, what’s priced, the planopen
The Saturday and Tuesday Journals, read together, Part II. This is everything in the two papers about the years, the money and the living. Social Security’s 2032 date and the 22% cut nobody has filed a bill for. A retired teacher’s $694,000 and the four documents that would have saved it. Overdeck and Ford family fortunes in court. El Niño heading for the Panama Canal and your grocery bill. Travel after a diagnosis. A wedding paid for by sponsors. A lake house on three television shows. The eclipse chasers booking 2027. And the Off Duty file, from a goalie who rates Caesar salads to the hairless he-men of summer. Part I, the markets side, is No. 163.
Part I of these two papers was about the price of money. Part II is about the price of everything else, and the dates attached to it. Social Security’s trust fund now has a year, 2032. The number to plan on is 78 cents on the dollar unless Congress writes a bill it has not written. A retired teacher’s savings were drained by the one relative she had cut out of her will. The four documents that would have stopped it cost a few hundred dollars. Read the Journal’s travel section as a planning document and it says the same thing from the other direction. The trips have a window. The eclipse has a date. The wedding has a price. The weather is now a line item in the grocery bill. None of this moves a model. All of it moves a plan.
The read is the same as Part I’s. The volatility index closed Monday at 14.92 and rose into Tuesday’s down tape. The three-month VIX still sits above spot. The crowd puts a September hike at 58%. Nothing in the life side of the papers changes it. What the life side adds is a reminder. A plan is built to survive the read being wrong. The Social Security cut lands in 2032 whether or not the Fed hikes in September. The teacher’s $694,000 left in a year the S&P 500 was up.
Crowd odds, not forecasts, pulled Tuesday, Sept. 1 at 2:20 p.m. Pacific: 81.5% that the Israel–Iran ceasefire holds through September 30 and 62% through year-end; 16.5% that the U.S. invades Iran before 2027
2.9% that WTI touches $120 in September; 61% that Washington announces the end of the Iranian blockade by December 31
89% that the Fed makes zero cuts in all of 2026. That is the number that matters for anyone planning on bond income, and for a 2032 Social Security gap that lower rates will not close
Crowd odds, not forecasts. Not investment advice.
four triggers from the life side of these two papers. If a parent over 80 handles their own money alone, the four documents (power of attorney, healthcare directive, a successor trustee who is not the caregiver, a trusted contact at each custodian) go in this month, not this year. If anyone in the household has had a diagnosis, the travel line moves to this year, and the insurance gets a pre-existing-condition waiver. If a child is getting married, set the parents’ number now and give it as a gift. And if your retirement income plan assumes 100 cents of Social Security after 2032, rerun it at 78.
Capital Wealth Daily · Vol. III · No. 164 · Wednesday, September 2, 2026. Reported from the Saturday/Sunday, August 29–30 and Tuesday, September 1, 2026 editions of The Wall Street Journal and from the Capital Wealth Growth Portfolio review notes. Figures are as reported at the Monday, August 31 close. Written and edited by the Capital Wealth LG research desk.