 Capital Wealth Daily
Relief Isn’t Repair
The bond selloff is running out of forced sellers. The reasons it started, $104 oil and a $1.993 trillion deficit, are still on the page.
The Journal’s Thursday story says the mechanical flows that deepened the Treasury selloff look close to spent. Those flows were mortgage-bond hedging and a futures contract about to switch bonds. The 10-year closed at 5.232% after touching 5.365% early Wednesday. The same paper had more. Brent rose 4.1% to $104.28 after a tanker was hit near Qatar. The fiscal-year deficit came in at $1.993 trillion, with interest taking more than $1 of every $5 of revenue. Freddie Mac’s 30-year mortgage hit 7.40%, its highest since November 2023. Stocks slipped. The S&P 500 fell 0.47% to 7,765.36 two sessions after its record, and the NYSE logged 268 new lows against 37 new highs.
Our TakeA rally built on hedges unwinding is relief, not repair. Keep safe money in bills near 4%, price any mortgage off 7.40%, and leave the long bond to the people who have to own it.
The long end got a break, for mechanical reasons. The Journal reports the hedging flows that deepened the Treasury selloff are fading. Mortgage-bond holders have mostly hedged. The futures contract that was about to switch to a longer bond has stopped forcing sales. The 10-year closed Thursday at 5.232% after 5.365% early Wednesday, a 24-year high. The 30-year reopening still cleared at 5.618%. The fiscal-year deficit came in at $1.993 trillion the same morning.
Stocks slipped two sessions after the record. The S&P 500 fell 0.47% to 7,765.36, 0.69% under Tuesday’s 7,818.93. The Nasdaq lost 1.25% and the semiconductor index 3.39% after a report that OpenAI’s revenue is running below what it signaled. Underneath, the NYSE had 37 new highs against 268 new lows, and the Nasdaq 63 against 441. The VIX closed at 15.41.
Oil jumped and the refiners hit records. A tanker was hit near Qatar, and Riyadh’s airport was struck for at least the third time since Tuesday. Brent rose 4.1% to $104.28 and WTI 3.64% to $91.49. Energy stocks gained 2.97%. Valero closed at a record $443.80, up 4.6%, held at 1.5% in 12 books, not chased. The written trim trigger, a published White House restriction on diesel exports, has not happened.
The household ledger moved the wrong way. Freddie Mac’s 30-year mortgage hit 7.40% (Bankrate 7.50%), the highest since November 2023, and 21% of sellers are cutting prices. The average money-market account pays 0.45%, while a 13-week bill auctioned at 4.050%. Jobless claims fell for a fifth straight week to 197,000. And an editorial put a date on Social Security. Benefits get an automatic 22% cut in 2032 if nothing changes.
The life side. A Cornwall photographer drove 900 miles with a bag of coins to keep a Scottish phone box in service. A 313-pound former Ravens lineman proved a 1990s math conjecture. An 83-year-old architect is selling his $1.495 million plastic flying saucer so his wife won’t have to. Alice Cooper still lives in the house he bought for $90,000 in 1972. And Crested Butte’s median home is $1.23 million eight years after Vail bought the hill.
Off Duty · The Human File
16 stories · 3 pictured · 13 listed
Copper lines work in a blackout, and Britain's are set to go. Check what still rides on yours
Copper's trick is working in a blackout, and it's being retired. List the landline, the alarm and a parent's medical pendant before the switch, not after.
Hold
A 313-pound lineman left the NFL for MIT. Nine years on, he's proved a 1990s conjecture
He left the NFL with a master's already earned and the PhD half-started. Plan a second act in hours as well as dollars, and quit only after the test run.
Hold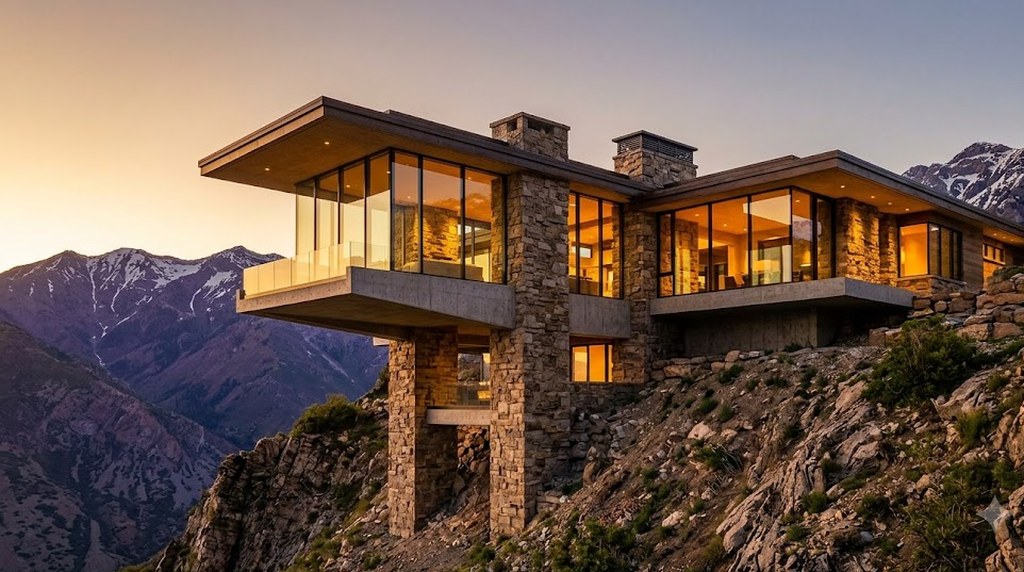
He's selling the flying-saucer house now so his wife won't have to later
He's selling the hardest-to-inherit thing he owns while he can still tell its story. Your odd assets need a named seller and a plan before your spouse needs one.
Hold- Mansion · House CallAlice Cooper's house: bought in 1972 for $90,000, still home, now with new ACHold
- Mansion · Ski & Mountain HomesAfter Vail: a $1.23 million median, a $25 million record pending and a second-home tax on the tableHold
- Mansion · Ski & Mountain HomesThree daughters, three suites, one rule at a $20 million Montana ski house: stay on budgetHold
- Mansion · Private PropertiesMcEnroe lists his $35M Malibu beach house and says he doesn't worry about the hazardsHold
- Mansion · Private PropertiesAsked $150 million, took $83.2 million. A neighbor plans to ask $165 millionHold
- Mansion · Private PropertiesLilly shares helped buy the butte, he says. Now 117 Jackson Hole acres sell for about $39.5 millionHold
- Mansion · Rich ZipsStowe's own data box: asks down 13%, listings up 16%. Yet the column's advice says move fastWatch
- Bookshelf · Baseball MemoirBaseball's record contract owed $300,000 a year to a kids' charity. It took lawsuits to collectHold
- Sports · BaseballA team on a third of the budget swept the Yankees. This time replay caught the fan at the wallHold
- Business & Finance · WineCalifornia could lose up to half its grape crop, and the growers are relievedHold
- Business & Finance · AirlinesThe airline behind 60% of U.S. involuntary bumps says it's done. Know the $2,150 number anywayHold
- Arts in Review · TelevisionA $7 million ransom and a fixer's 20%. The candidate gave the cash to his campaign that morningHold
- Business News · MediaRogan's Spotify renewal: terms like the last deal, 28.4 million listeners a week, one clientHold
Your Money & The Economy
13 stories · 3 pictured · 10 listed
A 7.40% mortgage, four price cuts, zero offers: the haggle has moved from the price to the rate
At these rates the real haggle is the financing, not the price. Price the payment at 7.4%, and weigh a seller's buydown against a cash cut before you sign.
Hold
Own the bond or the fund? Decide what the money's for first
A bond pays you back on a date. Many bond funds never do. That is the real difference, not convenience. Decide the job before the vehicle, and keep safe money short.
Hold
Social Security's cliff now has a year, 2032, and a size, 22%
Benefits shrink in 2032 under current law. They don't stop. Run your plan at 78 cents on the dollar, see what breaks, then check the claiming age.
Hold- Page One · Federal BudgetNearly $2 trillion in red ink, no recession to blame, and interest is the line nobody can vote awayHold
- Opinion · School ChoiceThe $3,400 school-choice credit now has rules, and 19 states plus D.C. still haven't said yesHold
- Opinion · PhilanthropyA $3 billion pledge to Carnegie Mellon, and what it says about any gift, at any sizeHold
- Page One · Personal Technology'Read-only' isn't 'private': an AI agent posted its owner's bank balances to the office SlackHold
- U.S. News · ImmigrationTwo big employers face a green-card suspension, and the six-year visa clock becomes a planning dateWatch
- U.S. Watch · Health InsuranceMichigan sues its biggest health insurer over prices, right at open-enrollment timeHold
- U.S. News · Hurricane IsaiasThe quiet hurricane season just ended: Isaias, a Category 2, heads for the Gulf CoastHold
- World News · SpainEvicted at 87 after decades in one apartment, and what a rental retirement needs written downHold
- Business & Finance · Logistics ReportRecord diesel, and the truckers who plugged in are the ones asking for helpHold
- Money & Investing · Tokenized StocksApple, Microsoft and Nvidia as blockchain tokens: ask what the wrapper adds, and what it takesAvoid
Markets & The Money
9 stories · 3 pictured · 6 listed
Midterm fourth quarters average 6.6%, and a 145-year study puts most of the gain after the vote
Certainty beats gridlock, Jakab argues. The 145-year study he cites puts the edge in the five months after Election Day. Go by a written date, not a hunch before the vote.
Hold
Refiners close at records before a projected bumper quarter. Valero is held, and the trim rule hasn't fired
We hold Valero at 1.5% in 12 books, bought Sept. 28, and the trim rule is a policy, not a price. No export restriction has been published, so it's held, not chased.
Hold
A tanker hit off Qatar, Riyadh's airport struck again, and Brent jumped 4.1%
Supply is being rerouted, not stopped. The energy sleeve (CVX, XOM, LNG, COP, EOG) already owns this risk. Held at weight, with nothing added at a war premium.
Hold- Markets · ChipsAn OpenAI revenue report knocked seven chip stocks at once, and Samsung fell on a bumper forecastWatch
- U.S. News · JobsClaims fall a fifth week to 197,000. A job market that won't crack keeps the Fed's next move liveHold
- Business News · ConsumerPepsiCo cut its profit outlook and the stock rose: what an income investor should take from itWatch
- Technology · TelecomA rocket company's $8 billion spectrum deal sank three dividend stocks more than 6% after the bellWatch
- U.S. News · DefenseA framework isn't revenue: Congress hasn't funded most of the Pentagon's dozen-plus munitions dealsHold
- Technology · Biotech IPOsBiotech IPOs almost triple; one trial sinks Argenx nearly 12%, one buyout lifts Pacira 44%Avoid
From the desk Bias, the book, what’s priced, the planopen
One paper, and a day the bond market exhaled for reasons that have nothing to do with the deficit. The lead, The Bond Selloff's Machinery Is Running Out of Road. The Reasons Aren't: the 10-Year at 5.232% After a 5.365% High, explains why a rally built on hedges unwinding doesn’t change what you should do with a mortgage or a bond fund. The life side leads, as always. There's the man who drove 900 miles with a bag of coins to keep a phone box alive, a 313-pound lineman who left the NFL for MIT and proved a 1990s conjecture, a plastic flying saucer listed at $1.495 million, Alice Cooper’s $90,000 house, Crested Butte eight years after Vail, a billionaire builder’s daughters designing their own suites, John McEnroe’s $35 million Malibu listing, a $150 million Florida ask that sold for $83.2 million, a Lilly scientist’s 117 acres in Jackson Hole, Stowe’s numbers, Dave Winfield’s charity clause, the Yankees swept by a third of their payroll, California’s welcome short harvest, the airline that stopped bumping, Joe Rogan’s renewal and a $7 million ransom on Netflix. Your Money runs the ledger. It covers the 7.40% mortgage, bond or bond fund, Social Security’s 2032 date, the $1.993 trillion deficit, the school-choice credit, a $3 billion gift, an AI agent that posted its owner’s bank balances, two employers suspended from sponsoring green cards, a state suing its biggest insurer, the first hurricane, an 87-year-old renter in Spain, diesel at the ports and tokenized shares. Then the markets. We cover the selloff that ran out of sellers, the midterm fourth quarter, the refiners’ record, oil, the chip wobble, jobless claims, PepsiCo, SpaceX’s $8 billion of spectrum, the Pentagon’s unfunded deals and biotech’s coin flips.
A down day with an odd shape. The S&P 500 fell 0.47% to 7,765.36 and the Nasdaq Composite 1.25% to 27,193.34, both two sessions off records. The Dow added 0.10% to 51,231.64, and the Russell 2000 was flat at 2,794.13. Technology fell 1.78% and the semiconductor index 3.39% on a report about OpenAI’s revenue. Financials rose 0.91% and energy 2.97% as Brent jumped 4.1% to $104.28 and WTI 3.64% to $91.49. On the NYSE more stocks rose than fell, 1,710 to 1,016, yet new 52-week lows swamped new highs, 268 to 37. On the Nasdaq it was 441 to 63. Treasurys rallied at the long end for a change. The 10-year closed at 5.232% from 5.276%, the 2-year at 4.753%, and the 30-year reopening cleared at 5.618%. Gold rose 0.44% to $4,131.80, still down 4.48% on the year. Freddie Mac’s 30-year mortgage came in at 7.40%, Bankrate’s at 7.50%. The VIX rose 2.19% to 15.41. Next dates: September inflation Wednesday, Oct. 14 · the Fed Oct. 27–28 · the vote Nov. 3.
Expected volatility by horizon at Thursday’s close. These are the 9-day, 30-day (the VIX), 3-month and 6-month Cboe indexes, our own pull. Rising left to right is the calm shape; the reverse is the stressed one.
- Vol-of-vol under 90 — 87.66 ThursdayPASS
- Core inflation at 0.1% or less — +0.27% in August; September’s report Wed., Oct. 14FAIL
- The Fed not raising — raised Sept. 16FAIL
Signals point to a calm surface and a market paying up for insurance. The VIX closed at 15.41. In our own Cboe pull Thursday, it sat well under the three-month (18.08) and six-month (20.04) readings. That is the shape vol takes when nothing is on fire. Vol-of-vol was 87.66, under the September letter’s 90 line, and the equity put/call ratio was 0.62, neither fear nor complacency. Against that, the SKEW index jumped to 149 from 142, which is big money paying for crash protection. The NYSE had 268 new lows on a day more stocks rose than fell. The 10-year still sits above 5.2% and Brent above $104. The two conditions that fail, core inflation and a Fed that raised, have dates. The September inflation report comes Wednesday, Oct. 14, and the Fed meets Oct. 27–28. None of this is a forecast.
The Journal’s own crowd market (Polymarket, 2:30 p.m. ET Thursday, $6.9 million traded) on the fed-funds rate at the end of 2026: 4.25% at 68%, 4% at 20%, 4.5% or higher at 10%. Our read is that one more quarter-point increase by December is the favorite, and the crowd has been moving that way all week.
Our own Polymarket pull, Friday 12:23 p.m. PT: for the Fed in October, no change 84% and a quarter-point increase 16%. For December, an increase 74% and no change 22%. Two increases in all of 2026, 70%. The 10-year reaching 5.4% before 2027: 69%. A U.S. diesel-export ban by Dec. 31: 12% (by Oct. 31: 2%). That is the crowd’s price on Valero’s trim trigger. The midterms: Democrats taking both chambers 62%, a split 29%, a Republican sweep 8%.
The borrowing table. Freddie Mac 30-year 7.40% (7.28% a week ago; the highest since November 2023); Bankrate 30-year 7.50% and 15-year 6.90%, both 52-week highs; the 5/1 ARM 6.42%, the one consumer rate that fell; a 48-month new-car loan 7.03%; prime 7.00%; the average money-market account 0.45%.
Market-implied expectations, not forecasts. They move intraday and have been wrong before. Not investment advice.
Three sittings, none of them a forecast. First, the mortgage. At 7.40%, price the payment before the house. If a seller offers to buy the rate down, ask what the same money does off the price instead. If you’re the seller, the 21% cutting prices are the market talking. Second, the bond question. Before you buy a bond or a bond fund, say what the money is for. A need with a date gets a bill or a ladder you hold to maturity. An open-ended need can own a fund. The 3-to-7-year Treasury fund that’s down 15% in price and flat in total return is why the answer matters. Third, Social Security. Run your plan at 78% of the statement’s number. If it still works, you have a cushion. If it doesn’t, the claiming age and the savings rate are the levers you control, and both work better the earlier you move them.
You don’t wait for the first drop to find the umbrella. If a 7.40% mortgage, a bond fund you didn’t pick, or a Social Security statement you haven’t reread is on your desk, bring it. Fifteen minutes is usually enough to find the one thing worth changing.
Book 15 minutes — phone or Zoom →Capital Wealth Daily · Vol. III · No. 182 · Friday, October 9, 2026. Reported from The Wall Street Journal of Friday, October 9, 2026 (Page One, U.S. and World News, Business & Finance, Heard on the Street, Arts in Review, the opinion pages, Sports and the Mansion section), whose market tables are the Thursday, October 8 close; Treasury yields are the Journal’s (Tullett Prebon / Tradeweb). The volatility readings by horizon, vol-of-vol, the SKEW and put/call figures are the desk’s own pull from Cboe data at Thursday’s close; prediction-market odds are the Journal’s own Polymarket box as printed and the desk’s own Polymarket pull at 12:23 p.m. PT on Friday, October 9, each labeled where it appears. We carry crowd odds as a price, not an endorsement of any platform. The September letter’s conditions and dates are the desk’s opinions, stated so they can be graded, and are not forecasts. Written and edited by the Capital Wealth LG research desk.